Stay Ahead, Stay ONMINE

PJM Moves to Redefine Behind-the-Meter Power for AI Data Centers

PJM Interconnection is moving to rewrite how behind-the-meter power is treated across its grid, signaling a major shift as AI-scale data centers push electricity demand into territory the current regulatory framework was never designed to handle. For years, PJM’s retail behind-the-meter generation rules allowed customers with onsite generation to “net” their load, reducing the amount […]

PJM Interconnection is moving to rewrite how behind-the-meter power is treated across its grid, signaling a major shift as AI-scale data centers push electricity demand into territory the current regulatory framework was never designed to handle.

For years, PJM’s retail behind-the-meter generation rules allowed customers with onsite generation to “net” their load, reducing the amount of demand counted for transmission and other grid-related charges. The framework dates back to 2004, when behind-the-meter generation was typically associated with smaller industrial facilities or campus-style energy systems.

PJM now argues that those assumptions no longer hold. The arrival of very large co-located loads, particularly hyperscale and AI data centers seeking hundreds of megawatts of power on accelerated timelines, has exposed gaps in how the system accounts for and plans around those facilities.

In February 2026, PJM asked the Federal Energy Regulatory Commission to approve a tariff rewrite that would sharply limit how new large loads can rely on legacy netting rules. The move reflects a broader challenge facing grid operators as the rapid expansion of AI infrastructure begins to collide with planning frameworks built for a far slower era of demand growth.

The proposal follows directly from a December 18, 2025 order from FERC finding that PJM’s existing tariff was “unjust and unreasonable” because it lacked clear rates, terms, and conditions governing co-location arrangements between large loads and generating facilities.

Rather than prohibiting co-location, the commission directed PJM to create transparent rules allowing data centers and other large consumers to pair with generation while still protecting system reliability and other ratepayers. In essence, FERC told PJM not to shut the door on these arrangements, but to stop improvising and build a formal framework capable of supporting them.

Why Behind-the-Meter Power Matters

Behind-the-meter arrangements have become one of the most attractive strategies for hyperscale and AI data center developers seeking to bypass grid bottlenecks. Across the PJM Interconnection footprint, particularly in Northern Virginia and other Mid-Atlantic markets, the queue for new grid service has become a strategic constraint.

Developers are trying to energize multi-hundred-megawatt campuses on accelerated timelines, while utilities and regional planners face transmission limits, slow generation additions, and growing debate over who should bear the cost of serving massive new loads. Those tensions have increasingly drawn the attention of regulators, policymakers, and consumer advocates.

PJM’s Board acknowledged in January 2026 that data centers account for a substantial share of forecast large-load additions and that their scale and speed are unlike anything the system has previously experienced. At the same time, PJM has made clear it does not intend to slow that growth. Instead, it wants the data center sector to participate more directly in addressing the reliability and affordability challenges its demand is creating.

At the center of the debate is the original purpose of behind-the-meter generation. PJM argues the framework was designed for relatively small industrial or campus-style systems and not for giant single-point loads sitting behind power plants.

Under existing rules, behind-the-meter generation allows a facility to net its load against its generation, which can leave large co-located loads effectively outside PJM’s planning assumptions. In materials presented at the May 2025 PJM Large Load Additions Workshop, PJM stated bluntly that “large load behind generation was not intended” under the current rules. The workshop also warned that such configurations may not be fully captured in forward-looking planning models, and in some cases may not even be fully visible to PJM if the generation is classified as retail rather than a PJM resource.

The concern is not theoretical. In testimony submitted to the Federal Energy Regulatory Commission in late 2024, PJM Chief Operating Officer Stu Bresler argued that co-located behind-the-meter loads are effectively excluded from PJM’s load forecasts. Electrically, they sit behind a generator, but the system’s planning models do not treat them as load the broader grid must ultimately be prepared to serve.

That disconnect creates a potential reliability risk. If a co-located generator fails or retires, the regional grid may suddenly be expected to supply a large load it was never planned to support. Bresler’s argument is not that such arrangements are impossible, but that the current framework creates a mismatch between physical reality, system planning obligations, and the political expectations that emerge once a major facility is operating.

In the era of AI-scale infrastructure, PJM argues, those mismatches become increasingly difficult to manage. For grid planners, the concern is simple. A data center sitting behind a power plant may appear invisible in the planning models … until the day the grid is expected to supply it.

Proposed 50 MW Threshold

PJM Interconnection’s February 2026 filing attempts to resolve the planning mismatch by drawing a clear line between traditional behind-the-meter generation and the new scale of data center demand.

The most consequential element is a proposed 50 MW threshold. Under the filing, new behind-the-meter loads larger than 50 MW would no longer qualify for the legacy netting treatment that allows customers to offset load with onsite generation.

PJM proposes a three-year transition period, and existing behind-the-meter arrangements would be grandfathered for the life of their contracts. Backup generation would not count toward the threshold. In practical terms, the rule is aimed squarely at the emerging class of mega-loads rather than smaller industrial or campus-style systems.

For data center developers, the change is significant. Netting has been attractive because it reduces the amount of load that appears on the transmission system, lowering exposure to certain grid-related charges. PJM now wants to reserve that treatment for smaller facilities while pushing large new loads into explicit transmission-service categories.

Alongside the filing, PJM proposed three new service constructs for co-located loads:

  • Interim Network Integration Transmission Service

  • Firm Contract Demand Transmission Service

  • Non-Firm Contract Demand Transmission Service

The rates and detailed terms for those services will be addressed in a subsequent filing, but the intent is already clear. PJM wants co-located data centers to move out of the gray zone between “on-system” and “off-system” status and instead select a defined service model with corresponding obligations and costs.

The proposal goes well beyond billing mechanics. It is part of PJM’s broader 2026 strategy for managing the surge of large-load development. In January, the PJM Board outlined a six-part framework that includes improved load forecasting, a larger role for state regulators, pathways for large loads to bring their own generation, a “connect-and-manage” model that allows earlier grid access with potential curtailment risk, an accelerated interconnection track for some resources, and a backstop procurement process to address near-term reliability gaps.

The underlying message to the market is plain. The legacy framework cannot accommodate a wave of multi-hundred-megawatt data centers arriving faster than the grid can add generation and transmission. Under PJM’s proposed rules, large loads will increasingly need to bring supply with them, accept operational limits, or pay more directly for the grid services they require.

In effect, PJM is signaling that AI-scale infrastructure can no longer rely on regulatory ambiguity to secure power access. For the next generation of AI campuses, access to power may depend less on proximity to generation and more on how transparently the load participates in the grid.

The Politics of Behind-the-Meter Power

The broader architecture PJM is proposing matters not only for grid planning but also for the politics surrounding large data center development.

For years, behind-the-meter arrangements were often presented as a way for data centers to reduce strain on the grid by supplying some of their own power. PJM’s recent posture is more cautious. While proximity to generation can offer operational benefits, PJM now argues that physical location alone does not resolve the system-level obligations created by very large loads.

A facility may sit next to a power plant, but it can still create planning, reliability, and cost-allocation challenges if the arrangement allows it to avoid paying for transmission infrastructure while remaining dependent on the broader grid when outages or operational disruptions occur.

Those concerns came into sharper focus during the high-profile dispute over a proposed arrangement between Amazon Web Services and Talen Energy involving co-located data center load at the Susquehanna nuclear facility in Pennsylvania. The Federal Energy Regulatory Commission rejected an amended interconnection service agreement that would have expanded behind-the-meter power use for the data center, citing concerns about reliability and potential cost impacts on other customers.

For regulators, the case became a clear illustration of the risks associated with large co-location arrangements. PJM’s latest filing can be interpreted as an effort to prevent future disputes of that kind from being resolved one project at a time.

At the same time, the proposed reforms are generating pushback from other industrial energy users. Trade groups such as the Industrial Energy Consumers of America and the PJM Industrial Customer Coalition argue that the changes could undermine the economics of long-standing behind-the-meter operations at manufacturing facilities.

Industry advocates warn that stricter treatment of co-located loads could make hundreds of megawatts of existing or planned industrial behind-the-meter generation uneconomic, particularly for combined heat and power systems that have historically relied on the netting framework.

That tension helps explain why PJM chose a 50 MW threshold and a transition period rather than eliminating behind-the-meter netting altogether. The filing appears designed to preserve the traditional framework for smaller facilities while separating very large data center loads from a tariff structure PJM believes was never intended to support them.

What This Means for Large-Scale Data Center Development

For developers of AI-scale campuses, the commercial implications are substantial. PJM’s broader large-load strategy effectively pushes the market toward two emerging models.

Bring Your Own Generation (BYOG).
Under this approach, a data center developer or a utility partner arranges new generation to arrive with the load. PJM’s Board explicitly endorsed voluntary BYOG and directed staff to develop an expedited interconnection track for projects that bring new supply online alongside large loads as a way to mitigate curtailment risk.

Connect-and-Manage.
Under this framework, a large load gains grid access more quickly but accepts the possibility of curtailment during stressed system conditions.

Both models are more explicit (and likely more expensive) than relying on legacy behind-the-meter netting rules. Analysts say PJM’s plan could accelerate direct partnerships between data center developers and independent power producers.

According to reporting by Reuters, the package could encourage more private pairings between large loads and new generation because the alternative may involve a more constrained and potentially more costly path through the regional grid framework. In the near term, that dynamic could favor gas-fired generation, which remains one of the few dispatchable resources capable of being deployed quickly at the scale the market is demanding, even as nuclear, storage, and other technologies remain part of the longer-term supply mix.

Redefining Behind-the-Meter Power in the AI Era

At a deeper level, PJM is attempting to redefine what “behind the meter” means in an era of AI-scale infrastructure.

Historically, the term implied a relatively simple arrangement: onsite generation supplying a facility that had limited dependence on the broader grid. PJM now argues those assumptions break down when the load in question is a 200 MW, 500 MW, or even 1 GW data center campus.

At that scale, a facility sitting behind a generator is no longer just a customer with onsite power. It becomes a regional planning issue, a capacity issue, a transmission issue, and potentially a political issue if the arrangement fails and the grid is expected to step in.

Previous tariff structures often obscured that reality. PJM’s new proposal attempts to force it into the open.

When the Federal Energy Regulatory Commission evaluates the filing, it will need to balance three competing priorities:

  1. Enabling faster interconnection for large loads and supporting economic growth.

  2. Protecting existing ratepayers from subsidizing bespoke power arrangements for the largest new customers on the grid.

  3. Preserving legitimate industrial behind-the-meter models that have long supported manufacturing and combined heat-and-power systems.

PJM’s proposal attempts to thread that needle by grandfathering existing arrangements, carving out smaller facilities, and pairing behind-the-meter reforms with new transmission service options and a broader large-load integration strategy.

This is not a minor tariff adjustment. It is one of the clearest signals yet that regional grid operators are moving from reacting to data center growth to structurally redesigning market rules around it.

For developers, the message is increasingly obvious. Securing fast access to power will no longer be as simple as locating next to a generator and labeling the arrangement “behind the meter.”

Large loads will increasingly need to demonstrate how they are supplying power, what level of grid service they expect, what curtailment risk they are willing to accept, and how the costs of those choices will be allocated.

In the PJM region, home to the largest concentration of data center development in the world, that represents a major shift. It may also become a template for how other markets respond as AI infrastructure collides with power systems that were never designed for the speed or scale of this new demand.

In the emerging gigawatt era of digital infrastructure, the question is no longer whether power can be found. The question is how transparently and at what cost the grid is expected to support it.
Shape
Shape
Stay Ahead

Explore More Insights

Stay ahead with more perspectives on cutting-edge power, infrastructure, energy,  bitcoin and AI solutions. Explore these articles to uncover strategies and insights shaping the future of industries.

Shape

AMD takes on Intel and Nvidia with new 256-core EPYC server CPUs

AMD EPYC, Intel Xeon, and Nvidia Vera represent three different approaches to the evolving data-centre CPU market, added Rawat. “AMD competes through high core density, memory capabilities and power efficiency, while Intel leverages its established enterprise ecosystem, platform compatibility and customer relationships. Nvidia is taking a different approach with Vera,

Read More »

Vår Energi selects SLB for integrated drilling services offshore Norway

@import url(‘https://fonts.googleapis.com/css2?family=Inter:wght@100..900&display=swap’); .ebm-page__main h1, .ebm-page__main h2, .ebm-page__main h3, .ebm-page__main h4, .ebm-page__main h5, .ebm-page__main h6 { font-family: Inter; } body { line-height: 150%; letter-spacing: 0.025em; } button, .ebm-button-wrapper { font-family: Inter; } .label-style { text-transform: uppercase; color: var(–color-grey); font-weight: 600; font-size: 0.75rem; } .caption-style { font-size: 0.75rem; color: color-mix(in srgb, currentColor 60%, transparent); } <!–> Vår Energi has selected SLB as its main integrated drilling services supplier for the Transocean Barents and Deepsea Bergen rigs on the Norwegian Continental Shelf. ]–> <!–> –> June 18, 2026 <!–> The energy technology company said the selection covers an initial 4-year period, with 4 additional 1-year extension options that could extend the scope through 2034. Two harsh-environment semisubmersibles will continuously drill exploration and development wells during this period. The selection expands SLB’s relationship with Vår Energi across drilling, digital well and field development planning, and subsea production systems.   ]–>

Read More »

EIA sees Brent near $100/bbl through yearend 2026 as Middle East supply constraints persist

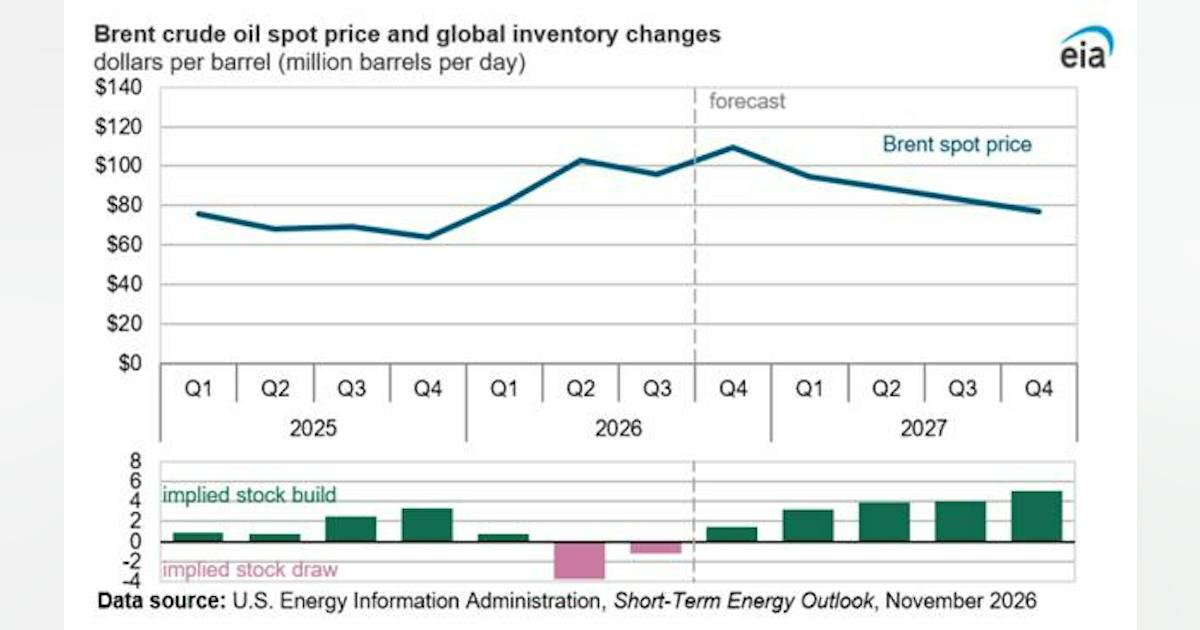
Global crude oil prices are expected to remain near $100/bbl through yearend 2026 as continued Middle East supply disruptions, tanker attacks, and constrained shipping capacity keep oil markets tight, the US Energy Information Administration (EIA) said in its November Short-Term Energy Outlook (STEO). EIA forecasts Brent crude oil spot prices will average about $100/bbl in November and December before gradually declining in 2027 as Middle East production recovers and global inventories rebuild. Brent is projected to average $97/bbl in 2026 and $86/bbl in 2027, falling to $77/bbl by fourth-quarter 2027. Brent averaged $124/bbl in October, up $10/bbl from September and the highest monthly average since July 2022 on an inflation-adjusted basis. Prices rose for a third consecutive month as declining inventories, tanker attacks in the Middle East and Black Sea, and higher shipping costs disrupted global oil flows. However, Middle East exports increased slightly in October following the restart of Saudi Arabia’s East-West Pipeline, according to Vortexa vessel-tracking data cited by EIA. Continued shipments through the Strait of Hormuz, supported by ship-to-ship transfers along Oman’s coast, also helped ease supply constraints. Brent fell below $100/bbl on Nov. 4. Middle East crude oil production shut-ins averaged an estimated 2.5 million b/d in October, down sharply from a peak of 10.9 million b/d in May. EIA expects disruptions to remain near 2.5 million b/d through fourth-quarter 2026 before declining to 1.9 million b/d in first-half 2027 and 1.3 million b/d in the second half. EIA assumes most Middle East production outside Iran will return to pre-conflict levels by mid-2027, supported by pipeline bypass routes, ship-to-ship transfers, and additional pipeline capacity in the United Arab Emirates. Iranian exports, however, are expected to remain constrained throughout the forecast period. Global oil inventories declined by an estimated 1.2 million b/d in third-quarter 2026 but are

Read More »

Salt Creek advances Delaware basin gas processing expansion

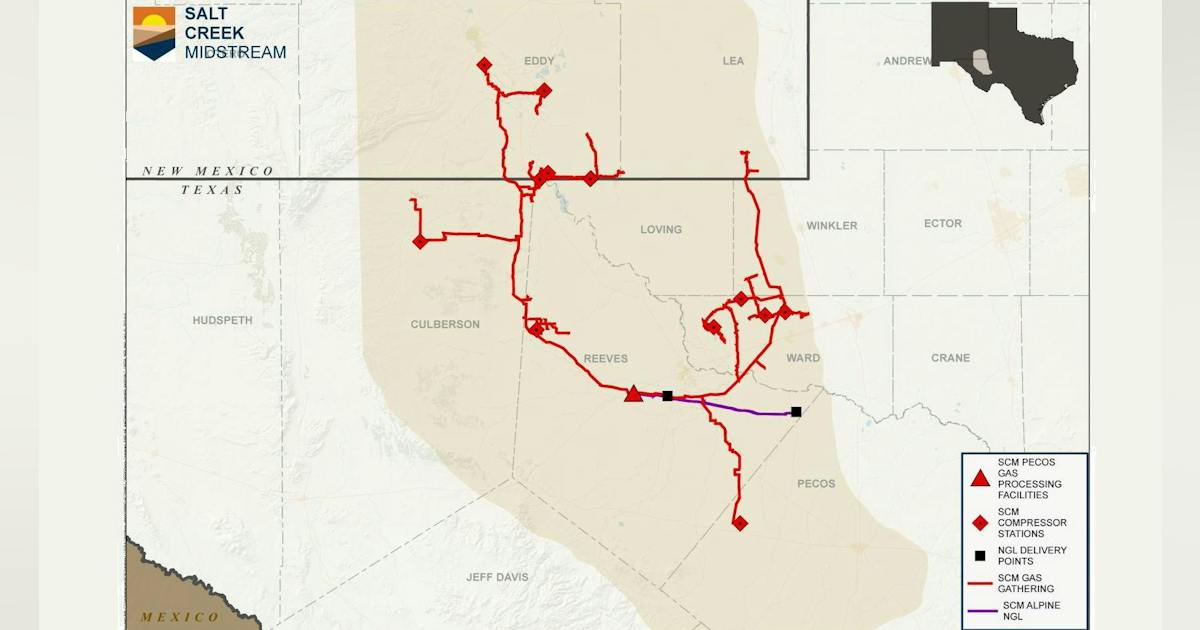
Salt Creek Midstream LLC has ordered long-lead equipment for a fourth cryogenic natural gas processing plant at its Pecos Processing Complex in Reeves County, Tex. Slated for final investment decision by yearend 2026, the proposed Pecos IV train project, if approved, would add up to 300 MMcfd of capacity and enter service in second-half 2028, the operator said in a release Nov. 11. Depending on a final capacity decision for the project, the expansion could lift the company’s overall installed Permian gas processing capacity to as much as 900 MMcfd. With the Pecos site designed for further expandability up to 1.2 billion bcfd from its current 600-MMcfd capacity, Salt Creek said it has also now secured grid power to support that potential buildout. The proposed project follows customer and volume growth across Salt Creek’s Delaware basin system, which the company said will exceed its existing system’s 600 MMcfd of processing capacity in first-half 2027. To support its planned Permian growth program, Salt Creek confirmed it has also secured strategic offloading contracts to provide firm processing capacity as a bridge to the planned expansions. Those offloads are scheduled to enter service by the end of first-quarter 2027, according to the operator. Salt Creek reported the addition of nearly 300,000 acres dedicated across the Permian’s eight core counties, following additional acreage commitments signed earlier in the year. The dedications cover more than 20 unidentified customers. The operator said it expects about 75% of anticipated 2027 throughput to come from investment-grade counterparties, while customer volume commitments to support about 35% of projected volumes. The company’s acreage position includes about 40,000 dedicated acres in the liquids-rich core of the Woodford fairway, along with additional exposure to prospective areas. Salt Creek estimated Woodford volumes to exceed 200 MMcfd by yearend 2027 based on more than

Read More »

No home left behind: Scaling VPP participation while maintaining customer control

Listen to the article 5 min This audio is auto-generated. Please let us know if you have feedback. Gisela Glandt is vice president of virtual power plants at Uplight, a provider of utility demand management solutions. Load growth is back, and it isn’t slowing down. Electrification, data centers and extreme weather are pushing utilities to find flexible capacity faster than they can build it. Demand-side programs including demand response, virtual power plants, time-varying rates and energy efficiency are one of the few levers that scale quickly and cost-effectively — yet the industry keeps hitting the same wall. Gisela Glandt Roughly 80% of customers say they want help managing their energy, but utilities are still seeing enrollment in demand management programs around 10% — despite larger incentives, more innovative technology, and more targeted marketing. What if the problem isn’t the customers and instead is the process of asking them to raise their hand? Opt-in utility program enrollment puts the burden on the customer: to understand the program, check to see if they are eligible, decide it’s worth it, and then take action. The benefits and incentives can show up months down the road, and they may even forget about them. Most people don’t make it past enrollment and it’s not because of lack of interest. It simply involves too many steps and too much brain power.  The industry is shifting from programs customers must join to flexibility that’s already embedded as a default or activated at the point of sale of a device, with no enrollment required. Where utilities have made this shift, customer participation climbs from 10% into the 70% to 100% range. One Midwestern utility that restructured a program from opt-in to opt-out scaled capacity four to five times faster — and had 70% to 80% of customers participate. 

Read More »

Planet One encounters hydrocarbons at Nya Gyidie-1X offshore Ghana

Planet One Oil & Gas has encountered hydrocarbons in the Nya Gyidie-1X exploration well on the Deepwater Cape Three Points (DWCTP) Block offshore Ghana, opening what the company describes as a new carbonate exploration play in the country. The well, drilled about 148 km offshore in 2,289 m of water, encountered hydrocarbons in carbonate reservoirs between 3,364 m and 3,499 m measured depth. Planet One said further technical evaluation is under way to determine the discovery’s size and commercial potential. According to the operator, Nya Gyidie-1X is Ghana’s first successful test of a Cenomanian-Turonian carbonate reservoir system as a primary exploration target. Most of the country’s commercial oil and gas discoveries to date have been associated with sandstone reservoirs. “The significance of Nya Gyidie-1X goes beyond the hydrocarbons encountered in this well,” said Kwame Ntow Amoah, chief executive officer of Ghana National Petroleum Corp. “For the first time in Ghana, we have tested and confirmed hydrocarbons in a carbonate reservoir system, opening up a new geological play for further exploration.” The DWCTP block covers about 1,454 sq km in the Deepwater Tano basin. Planet One operates the block with partners GOIL Upstream Ltd. and Ghana National Petroleum Corp.

Read More »

Chevron signs Namibia license farm-out deal with QatarEnergy

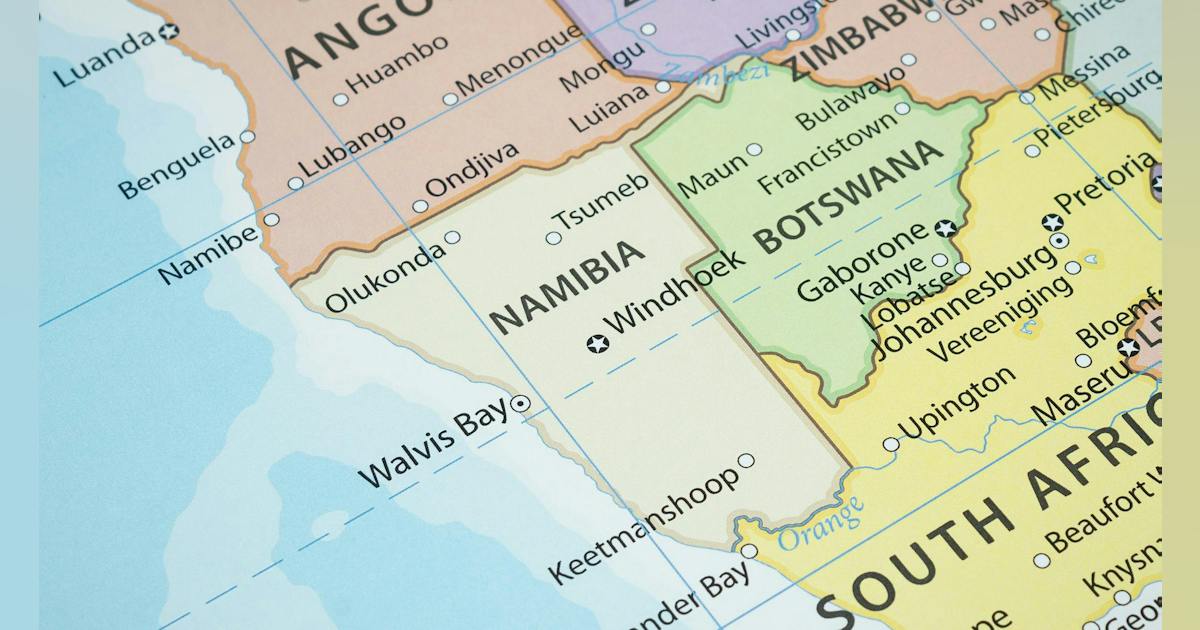
@import url(‘https://fonts.googleapis.com/css2?family=Inter:wght@100..900&display=swap’); .ebm-page__main h1, .ebm-page__main h2, .ebm-page__main h3, .ebm-page__main h4, .ebm-page__main h5, .ebm-page__main h6 { font-family: Inter; } body { line-height: 150%; letter-spacing: 0.025em; } button, .ebm-button-wrapper { font-family: Inter; } .label-style { text-transform: uppercase; color: var(–color-grey); font-weight: 600; font-size: 0.75rem; } .caption-style { font-size: 0.75rem; color: color-mix(in srgb, currentColor 60%, transparent); } Chevron Corp. has agreed to farm out to QatarEnergy a partial, non-operated interest in an exploration block offshore Namibia. Financial details were not disclosed.   Through the agreement, Chevron subsidiary Chevron Namibia Exploration II Ltd. will farm out 25% interest in Petroleum Exploration License 0082 (PEL82), comprising blocks 2112B and 2212A in Walvis basin, QatarEnergy said in a release this week. Upon completion of the deal, Chevron will remain operator of the block with 55% interest. Namcor E&P and Custos Energy will each hold a 10% interest. PEL82 covers an area of about 11,444 sq km in water depths of 350-2,300 m. Chevron acquired an 80% operated interest in the license in 2024 through a farm-in deal with National Petroleum Corp. of Namibia (Namcor). At the time of Chevron’s farmout with Namcor, about 70% of the total block area was covered by existing seismic (3,500 km of 2D and 9,500 sq km of 3D) data. Previous drilling activity on the license included the Murombe-1 and Wingat-1 wells. Results confirmed regional extension and presence of the Barremian-Aptianoil-prone source rock (Kudu shale). The Murombe-1 penetrated the Baobab sands with about 20% porosity. The Wingat-1 well recovered 38-41° API oil to surface.

Read More »

Jensen Huang Resigns as NVIDIA CEO, Sending Shockwaves Through AI Data Center Industry

NVIDIA co-founder Jensen Huang resigned Thursday morning (November 12) as president, CEO and board member of the world’s dominant AI chipmaker, a stunning leadership change that introduces new uncertainty into the global artificial intelligence infrastructure boom. In an official announcement, NVIDIA confirmed that Chief Financial Officer Colette Kress will serve as interim CEO while the board conducts a search for Huang’s permanent successor. The company also appointed longtime director Harvey C. Jones as its first board chairman. The departure ends Huang’s 33-year leadership of the company he co-founded in 1993 and comes amid a rapidly escalating controversy involving his reported personal relationships, potential Chinese intelligence activity and questions about corporate governance. According to Reuters, NVIDIA shares fell more than 10% in premarket trading Thursday as investors weighed the implications for the approximately $4 trillion company and the wider AI technology sector. The company’s announcement did not specify a reason for Huang’s resignation. National Security Investigation Precedes Leadership Change The leadership shakeup follows several days of increasing scrutiny over Huang’s reported relationship with a businesswoman whom U.S. authorities suspect of connections to Chinese intelligence, alongside separate reporting concerning a relationship with a senior NVIDIA executive. On November 8, NVIDIA’s board announced an independent investigation into whether Huang had been targeted by a foreign intelligence operation. At the time, directors stated that they had no reason to believe company secrets or national security had been compromised. The controversy subsequently attracted congressional attention, including calls for Huang’s resignation and questions about semiconductor export controls and the security of advanced AI technology. The espionage allegations remain contested, and no compromise of NVIDIA technology has been publicly established. For the data center industry, however, the immediate question extends beyond the circumstances of Huang’s departure. It concerns the potential disruption of an infrastructure ecosystem increasingly organized

Read More »

Google’s Utah Deal Puts Geothermal Power on the Data Center Map

In Taiwan, the Work Begins With Access to Land Google’s first geothermal procurement agreements in Asia call for an initial 10 MW of new generation on Taiwan’s grid to support local data centers and offices. When Google and developer Baseload Capital announced the agreements in April 2025, a Google energy executive told Taiwan Public Television Service that the companies expected operations to begin in 2029. The original timetable allowed roughly four years between signing a customer and delivering electricity. Baseload’s development work in Hualien County illustrates one reason such projects take time. In November 2025, the company reported that members of the Hongye Tribe had voted to approve a public-land lease for geothermal exploration. Baseload opened a local office, reached an agreement with the community, and secured an exploration permit for a two-year program of drilling in stages. The company has described Hongye separately from Google’s contracted supply. What the Hualien project documents is an early milestone rarely visible in a power purchase announcement: the developer secured community consent before drilling could establish what the field might produce. Kenya Has the Generating Field. The Campus Remains Unresolved. In Kenya’s Rift Valley, the appeal of Olkaria was evident when Microsoft and G42 announced their digital investment initiative in 2024. Kenya already had a fleet of geothermal generating stations at Olkaria. G42 and local partners proposed building a campus there, powered by geothermal electricity and hosting Microsoft Azure services for a new East Africa cloud region. Two difficulties emerged. In May 2026, Semafor reported that President William Ruto had cited insufficient available power as an obstacle to the project. Separately, Reuters, citing Bloomberg, reported disagreements over payment guarantees. Microsoft and G42 had sought a commitment from the Kenyan government to buy a certain amount of computing capacity annually. Kenya’s principal secretary for

Read More »

Alberta’s Gigawatt Play: Why Building Data Centers Means Building an Industry

For Alberta’s emerging data center industry, the difference between a roadmap and an excavator has become increasingly consequential. A few years ago, Western Canada’s data center conversation revolved around the possibilities: abundant energy resources, available land, a favorable climate and the prospect of attracting hyperscale investment to a region better known for oil, gas and other industrial development. Today, earthmoving equipment is preparing the ground for what is expected to become Canada’s largest data center, and the questions facing the province have changed accordingly. The shift was on display at Data Centre West 2026, held in Calgary in September, where some 500 industry and government leaders gathered to examine the infrastructure and policy requirements of Alberta’s rapidly expanding digital economy. But for conference founder Vlad Oujegov, the most revealing development wasn’t simply the appearance of projects measured in gigawatts. It was the growing recognition that building those projects will require Alberta to develop an entire supporting industry, while confronting the environmental, political and community questions that increasingly accompany large-scale AI infrastructure. “The theme last year was the data center roadmap,” Oujegov told Data Center Frontier Editor in Chief Matt Vincent during a new episode of the Data Center Frontier Show podcast. “This year’s theme really to me was about execution and actually getting things done, actually seeing projects materialize and construction beginning.” Oujegov is president and founder of the Western Canada Data Centre Alliance, which organizes Data Centre West, and serves as National Data Center Power Systems Lead at Schneider Electric. His perspective draws on both Alberta’s emerging development pipeline and the wider industrial ecosystem now being assembled around it. In DCF’s earlier reporting from Data Centre West 2026, the central question was how quickly Alberta could convert growing hyperscale demand into deliverable capacity. The latest podcast conversation takes that

Read More »

Data center champions lose badly as ballot initiatives target AI infrastructure

In other locales, data centers lost badly. In Joliet Township, Illinois, a restriction on new data centers passed with 80% of the vote. In Hubbard, Ohio, more than three-quarters of voters gave data centers a thumbs down. Ohio emerged as the main battleground, accounting for 21 of the 50 measures tracked by Ballotpedia. The votes covered several different approaches to controlling development: outright bans, power-consumption thresholds, temporary permitting moratoriums, mandatory public votes and requirements for developers seeking tax incentives. California and Florida saw outright bans. California voters in the cities of Alhambra and Monterey Park, where voters approved a measure prohibiting data centers. In Florida, Edgewater voters approved a charter amendment opposing new data centers and expansions of existing facilities.

Read More »

Land & Expand: Texas’ AI Boom Meets a New Political Reality

Hut 8 Advances a Gigawatt-Scale Campus Near Corpus Christi Another significant development came November 4, when Hut 8 reported continued progress on its Beacon Point AI data center campus in the Corpus Christi region. The company said that its previously announced second 352 MW IT-capacity lease had fully commercialized the campus, bringing the total contracted IT capacity associated with the two phases to 704 MW. The campus is designed around approximately 1 GW of utility capacity, a separate measure from the critical IT load under lease. Hut 8 estimates approximately $19.6 billion in base-term contract value across the two phases. In its third-quarter results, the company said construction of the campus substation had begun, alongside foundation and underground utility work for the first phase. Initial data hall delivery is targeted for the third quarter of 2027, with the second phase targeted for the second quarter of 2028. The company also disclosed agreements to acquire two energized sites in West Texas, with up to 230 MW of utility capacity at full energization, subject to outstanding approvals and infrastructure development. Those acquisitions point to another important trend: the increasing value of existing electrical infrastructure and sites that can potentially be adapted to serve advanced computing. As new greenfield projects face lengthy power studies and regulatory requirements, already energized locations may offer an alternative route to capacity. The distinction is especially important in markets such as Dallas-Fort Worth, where DCF’s analysis of CBRE’s first-half 2026 data found that approximately 95% of the region’s 765 MW under construction had already been preleased. PowerHouse and Big Watt Win Approval for Taylor Technology Campus Not every large new project is meeting resistance at the municipal level. On October 8, the City of Taylor approved a development agreement with PowerHouse Data Centers and Big Watt Digital for

Read More »

Google targets AI’s next infrastructure bottlenecks with two new TPUs

“It’s like adding more lanes to the highway,” he observed. “We’re not necessarily making each car travel faster, we’re creating more capacity so more traffic can move through the system at the same time.” Handling bursts, idling However, an agentic workload doesn’t behave exactly like a traditional inference workload. “It is bursty, long running, but often idle,” Lohmeyer noted. While it might generate outputs and call tools, it still has to wait for a response, maybe from a human, “literally for days.” During that time, it doesn’t need to do anything; it just needs to preserve context. But if resources are tied up for that entire multi-day period, they’re being wasted “90% plus of the time,” he said. Google Cloud’s open source TPU Sync is designed to address these issues by unifying memory, storage, and networking in software. The model-state layer for TPUs turns chip high bandwidth memory (HBM), host DRAM, shared storage, and the data center network into a “single, co-designed memory hierarchy,” the company said. It automatically tiers KV caches off the chip in milliseconds, streams context across nodes, and synchronizes RL weights to cut transfer latency and Time to First Token (TTFT) by more than 90%.

Read More »

Microsoft will invest $80B in AI data centers in fiscal 2025

And Microsoft isn’t the only one that is ramping up its investments into AI-enabled data centers. Rival cloud service providers are all investing in either upgrading or opening new data centers to capture a larger chunk of business from developers and users of large language models (LLMs).  In a report published in October 2024, Bloomberg Intelligence estimated that demand for generative AI would push Microsoft, AWS, Google, Oracle, Meta, and Apple would between them devote $200 billion to capex in 2025, up from $110 billion in 2023. Microsoft is one of the biggest spenders, followed closely by Google and AWS, Bloomberg Intelligence said. Its estimate of Microsoft’s capital spending on AI, at $62.4 billion for calendar 2025, is lower than Smith’s claim that the company will invest $80 billion in the fiscal year to June 30, 2025. Both figures, though, are way higher than Microsoft’s 2020 capital expenditure of “just” $17.6 billion. The majority of the increased spending is tied to cloud services and the expansion of AI infrastructure needed to provide compute capacity for OpenAI workloads. Separately, last October Amazon CEO Andy Jassy said his company planned total capex spend of $75 billion in 2024 and even more in 2025, with much of it going to AWS, its cloud computing division.

Read More »

John Deere unveils more autonomous farm machines to address skill labor shortage

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More Self-driving tractors might be the path to self-driving cars. John Deere has revealed a new line of autonomous machines and tech across agriculture, construction and commercial landscaping. The Moline, Illinois-based John Deere has been in business for 187 years, yet it’s been a regular as a non-tech company showing off technology at the big tech trade show in Las Vegas and is back at CES 2025 with more autonomous tractors and other vehicles. This is not something we usually cover, but John Deere has a lot of data that is interesting in the big picture of tech. The message from the company is that there aren’t enough skilled farm laborers to do the work that its customers need. It’s been a challenge for most of the last two decades, said Jahmy Hindman, CTO at John Deere, in a briefing. Much of the tech will come this fall and after that. He noted that the average farmer in the U.S. is over 58 and works 12 to 18 hours a day to grow food for us. And he said the American Farm Bureau Federation estimates there are roughly 2.4 million farm jobs that need to be filled annually; and the agricultural work force continues to shrink. (This is my hint to the anti-immigration crowd). John Deere’s autonomous 9RX Tractor. Farmers can oversee it using an app. While each of these industries experiences their own set of challenges, a commonality across all is skilled labor availability. In construction, about 80% percent of contractors struggle to find skilled labor. And in commercial landscaping, 86% of landscaping business owners can’t find labor to fill open positions, he said. “They have to figure out how to do

Read More »

2025 playbook for enterprise AI success, from agents to evals

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More 2025 is poised to be a pivotal year for enterprise AI. The past year has seen rapid innovation, and this year will see the same. This has made it more critical than ever to revisit your AI strategy to stay competitive and create value for your customers. From scaling AI agents to optimizing costs, here are the five critical areas enterprises should prioritize for their AI strategy this year. 1. Agents: the next generation of automation AI agents are no longer theoretical. In 2025, they’re indispensable tools for enterprises looking to streamline operations and enhance customer interactions. Unlike traditional software, agents powered by large language models (LLMs) can make nuanced decisions, navigate complex multi-step tasks, and integrate seamlessly with tools and APIs. At the start of 2024, agents were not ready for prime time, making frustrating mistakes like hallucinating URLs. They started getting better as frontier large language models themselves improved. “Let me put it this way,” said Sam Witteveen, cofounder of Red Dragon, a company that develops agents for companies, and that recently reviewed the 48 agents it built last year. “Interestingly, the ones that we built at the start of the year, a lot of those worked way better at the end of the year just because the models got better.” Witteveen shared this in the video podcast we filmed to discuss these five big trends in detail. Models are getting better and hallucinating less, and they’re also being trained to do agentic tasks. Another feature that the model providers are researching is a way to use the LLM as a judge, and as models get cheaper (something we’ll cover below), companies can use three or more models to

Read More »

OpenAI’s red teaming innovations define new essentials for security leaders in the AI era

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More OpenAI has taken a more aggressive approach to red teaming than its AI competitors, demonstrating its security teams’ advanced capabilities in two areas: multi-step reinforcement and external red teaming. OpenAI recently released two papers that set a new competitive standard for improving the quality, reliability and safety of AI models in these two techniques and more. The first paper, “OpenAI’s Approach to External Red Teaming for AI Models and Systems,” reports that specialized teams outside the company have proven effective in uncovering vulnerabilities that might otherwise have made it into a released model because in-house testing techniques may have missed them. In the second paper, “Diverse and Effective Red Teaming with Auto-Generated Rewards and Multi-Step Reinforcement Learning,” OpenAI introduces an automated framework that relies on iterative reinforcement learning to generate a broad spectrum of novel, wide-ranging attacks. Going all-in on red teaming pays practical, competitive dividends It’s encouraging to see competitive intensity in red teaming growing among AI companies. When Anthropic released its AI red team guidelines in June of last year, it joined AI providers including Google, Microsoft, Nvidia, OpenAI, and even the U.S.’s National Institute of Standards and Technology (NIST), which all had released red teaming frameworks. Investing heavily in red teaming yields tangible benefits for security leaders in any organization. OpenAI’s paper on external red teaming provides a detailed analysis of how the company strives to create specialized external teams that include cybersecurity and subject matter experts. The goal is to see if knowledgeable external teams can defeat models’ security perimeters and find gaps in their security, biases and controls that prompt-based testing couldn’t find. What makes OpenAI’s recent papers noteworthy is how well they define using human-in-the-middle

Read More »

Introducing Gemini 4 Hydrogen

Unlocking efficiencies in multi-model workloadsIn real-world software development, while teams rely on frontier models like Carbon and Argon for deep architectural judgment when designing systems

Read More »