Oil, fundamental analysis
Several factors whipsawed crude prices this week with WTI seeing a $12/bbl Hi/Lo spread. Varying accounts of flowing oil, ongoing infrastructure attacks, and sparse diplomatic efforts provided a great deal of market uncertainty.
WTI’s High was Monday’s $101.10/bbl for October while the Low was Wednesday’s $88.70. October Brent crude hit its High on Thursday at $108.25/bbl with the low on Tuesday at $97.35. WTI is down on the week while Brent is essentially flat. The WTI/Brent spread has blown out to $11.70. Analysts attribute this anomaly to a possible US diesel export ban making the domestic crude less desirable.
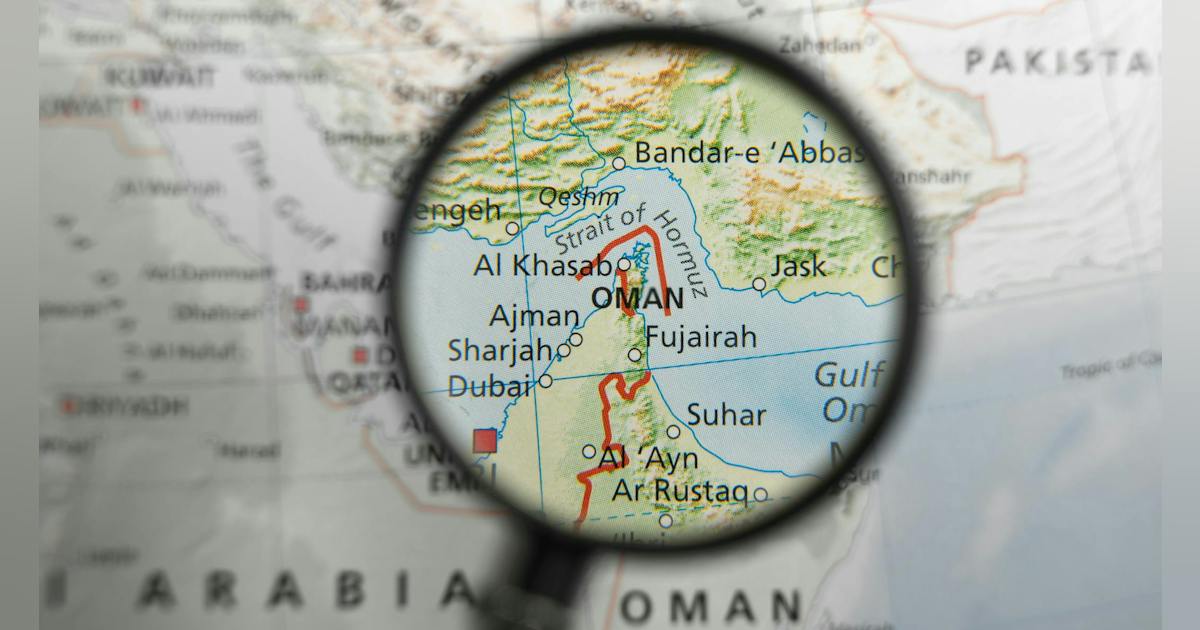
Saudi Arabia reported that flows in their East-West pipeline have resumed. However, Houthi rebels continue their strikes against Saudi Arabia which now includes attacks near Riyadh. The Yemeni-based rebel group has also targeted Saudi Aramco facilities at the port of Yanbu, the terminus for the East-West oil pipeline where it is loaded for export. The Kingdom’s military has been able to intercept several missiles launched by the Houthis. France has promised to send varied aid to help protect this key port and refinery there. Both the Saudis and Oman have appealed to Washington to keep the economic and military pressure on Iran even if the Iranians wish to start diplomatic talks again. Qatar is proposing that negotiations begin again as soon as next week in Oman. Some sources are indicating that Iran would consider opening the Strait of Hormuz if the US would rollback the naval blockade. This despite the strong words of defiance spoken by the leaders of both Iran and Israel at the UN this week.
Even with the continuing attacks, an estimated 5.5 million b/d of oil has been moving out of Yanbu and from UAE’s Fujairah port in the Gulf of Oman. However, that is down from June’s 7.8 million b/d. And the ship-to-ship transfers utilized are very costly. Meanwhile, the International Energy Agency (IEA) reported that global oil inventories have dropped by 507 million bbl since the start of the Iran war (about 2.8 million b/d). Estimates for August are another 95 million bbl decline.
The Energy Information Administration’s (EIA) Weekly Petroleum Status Report indicated that commercial crude oil inventories for last week increased while production held at 13.9 million b/d. The SPR was down 400,000 bbl to 284.5 million bbl (the lowest level since 1982).
Orders for durable goods in August were even with July vs. an expectation that they would be 0.3% lower. Claims for unemployment benefits were 197,000 vs. a forecasted 201,000. All three major US stock indexes are positive on the week due to the lower oil prices. The USD is higher also which does put downward pressure on crude prices. Gold is down.