Next week, much of the industry will gather in Las Vegas for RE+ to talk about what gets built next. It’s an important conversation, but I’d encourage asset owners to bring a second question with them: what more can we get from what’s already been built?
This question matters more than ever as electricity demand climbs and customers feel it on their monthly bill. EIA expects consumption to grow another 3.1% in 2027, driven largely by data centers and other commercial loads, while residential customers will pay nearly 5% more for power this year.
The industry is working hard to add capacity, but getting it built takes time. According to Lawrence Berkeley National Laboratory and GridTracker, the median project built in 2025 spent more than five years moving from interconnection request to commercial operation and only 13% of the capacity that requested interconnection between 2000 and 2020 had come online by the end of 2025. New generation is essential, but the fleet already operating is an opportunity we can’t afford to pass up.
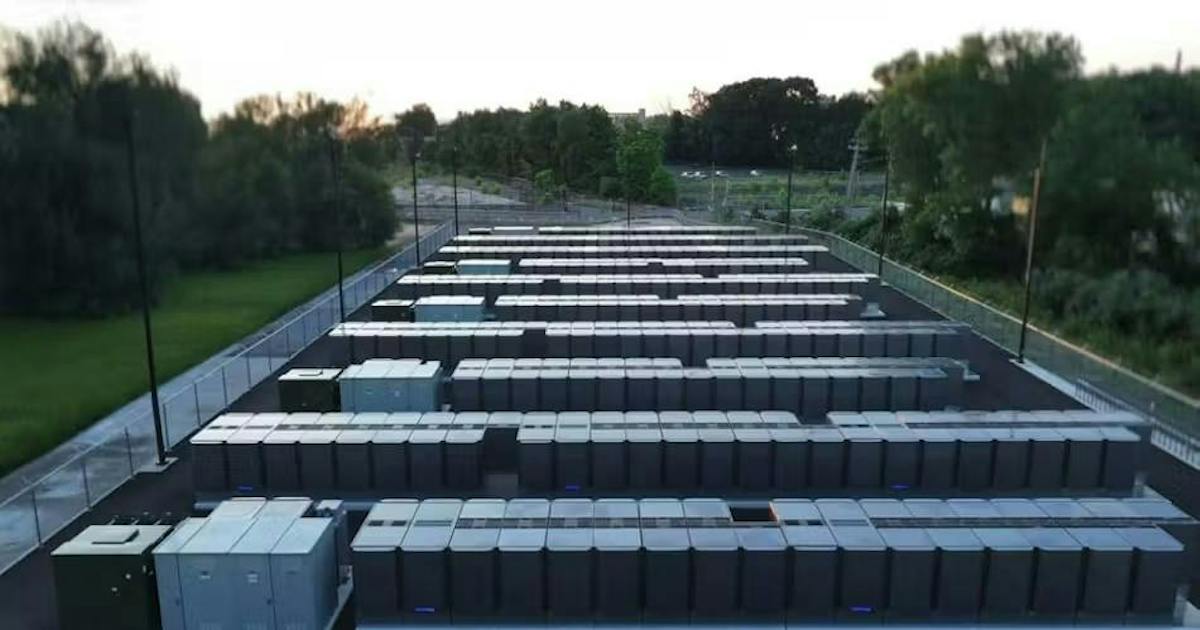
With nearly 52 gigawatts (GW) of utility-scale battery storage operating in the U.S. as of mid-2026, the installed base is too large to overlook and performance across it varies widely. When a battery energy storage system (BESS) falls short, the instinct is often to blame the battery and reach for augmentation or replacement, but in many cases the bottleneck is the controls, software and integration around it.
Operating assets are under more pressure
Higher prices should raise the value of delivering power when and where the grid needs it, yet revenues for many operating assets are moving in the other direction. In ERCOT, the average battery earned 84% less in 2025 than at its 2023 peak, as more storage competed for the same services. With incentive economics shifting too, asset managers face real pressure to get more from existing assets.
At the same time, utilities are leaning on storage for grid stability. As more gas units face revenue pressure and retirement, the grid loses the spinning mass that provides inertia in the first moments of a disturbance. Grid-forming inverters can replace that inertia, often by upgrading existing storage rather than building new. Providing that support, alongside peak shaving, load shifting and voltage and frequency regulation, takes controls that respond faster than many legacy SCADA and EMS platforms were built to handle.
Compliance requirements are moving just as quickly, with FERC Order No. 901 directing NERC to develop new reliability standards for inverter-based resources, including batteries, through 2030. Many plants operating today were designed before those requirements existed, increasing the importance of controls that can evolve as grid codes change. The same logic also applies to solar and wind plants. Once control functions are proven in the field they can easily be applied to other assets across the whole market.
The battery isn’t always the bottleneck
A recent Gridmatic study of 30 California batteries shows what’s at stake, with fleetwide availability averaging just under 80% and execution and bidding strategy driving a wide gap between top and bottom performers. Had every asset matched the leader, the group would have earned an estimated $98 million more over two years. The lesson isn’t that every performance gap can be solved with software. It’s that owners shouldn’t assume the battery itself is the limiting factor.
Before committing additional capital, owners should examine the full system: controls, software, market strategy, integration and plant-level coordination alongside battery health and hardware performance.
Think about the smartphone in your pocket. Its hardware may be several years old, but software updates can improve how it performs and add capabilities that weren’t available when you bought it. Storage assets aren’t so different: the physical equipment may still have years of useful life, while the controls and software around it can evolve to meet new market and grid requirements.
A modern energy management and plant control platform layered onto existing assets can help owners:
- Respond faster and more precisely to grid signals and market opportunities
- Meet new grid code requirements through software rather than hardware
- Expand operational flexibility and support additional value streams
- Maximize usable energy through balancing and intelligent power allocation
- Extend the competitive life of existing assets
A controls retrofit in practice
We saw this firsthand in the U.K., where our team, then part of Wärtsilä, worked with Zenobē to retrofit an existing 100 MW/100 MWh battery site with a new GEMS power plant controller. The upgrade took over energy management, secured grid compliance and added stateful grid-code functions such as de-load, along with control for multiple tenants sharing one point of interconnection.
The batteries stayed in place, but the site gained new capabilities and is better prepared for future requirements. That same approach translates to U.S. markets, where interconnection rules and local regulations are evolving quickly.
New deployments will remain critical, but the next wave of value may come from making today’s fleet work harder. As the industry gathers at RE+, owners should ask not just what they need to build next, but what more the assets already on the grid could deliver. Before replacing hardware or adding capacity, diagnose the whole plant. The constraint may not be the battery cells.