Stay Ahead, Stay ONMINE

Deep Data Center: Neoclouds as the ‘Picks and Shovels’ of the AI Gold Rush

In 1849, the discovery of gold in California ignited a frenzy, drawing prospectors from around the world in pursuit of quick fortune. While few struck it rich digging and sifting dirt, a different class of entrepreneurs quietly prospered: those who supplied the miners with the tools of the trade. From picks and shovels to tents […]

In 1849, the discovery of gold in California ignited a frenzy, drawing prospectors from around the world in pursuit of quick fortune. While few struck it rich digging and sifting dirt, a different class of entrepreneurs quietly prospered: those who supplied the miners with the tools of the trade. From picks and shovels to tents and provisions, these providers became indispensable to the gold rush, profiting handsomely regardless of who found gold.

Today, a new gold rush is underway, in pursuit of artificial intelligence. And just like the days of yore, the real fortunes may lie not in the gold itself, but in the infrastructure and equipment that enable its extraction. This is where neocloud players and chipmakers are positioned, representing themselves as the fundamental enablers of the AI revolution.

Neoclouds: The Essential Tools and Implements of AI Innovation

The AI boom has sparked a frenzy of innovation, investment, and competition. From generative AI applications like ChatGPT to autonomous systems and personalized recommendations, AI is rapidly transforming industries. Yet, behind every groundbreaking AI model lies an unsung hero: the infrastructure powering it. Enter neocloud providers—the specialized cloud platforms delivering the GPU horsepower that fuels AI’s meteoric rise. Let’s examine how neoclouds represent the “picks and shovels” of the AI gold rush, used for extracting the essential backbone of AI innovation.

Neoclouds are emerging as indispensable players in the AI ecosystem, offering tailored solutions for compute-intensive workloads such as training large language models (LLMs) and performing high-speed inference. Unlike traditional hyperscalers (e.g., AWS, Azure, Google Cloud), which cater to a broad range of use cases, neoclouds focus exclusively on optimizing infrastructure for AI and machine learning applications. This specialization allows them to deliver superior performance at a lower cost, making them the go-to choice for startups, enterprises, and research institutions alike.

The analogy to historical gold rushes is striking: just as miners relied on suppliers of picks and shovels to extract value from the earth, today’s AI pioneers depend on neocloud providers and chipmakers to access the computational resources needed to unlock insights and drive innovation. Neoclouds don’t compete in creating AI applications themselves; instead, they profit by enabling others to do so. This business model positions them as foundational players in the AI economy—profiting regardless of which companies or applications ultimately dominate the market.

Why Neoclouds Are Surging: Four Key Advantages

As AI development accelerates, the demand for compute is outpacing even the hyperscale cloud’s capacity to deliver. Training a foundation model like GPT-4 can require tens of thousands of GPUs running continuously for weeks—something traditional providers weren’t architected to support at scale. Enter the neoclouds: leaner, purpose-built platforms designed to meet the needs of modern AI workloads with greater precision and speed.

Here’s how they’re closing the gap:

1. Specialized Hardware

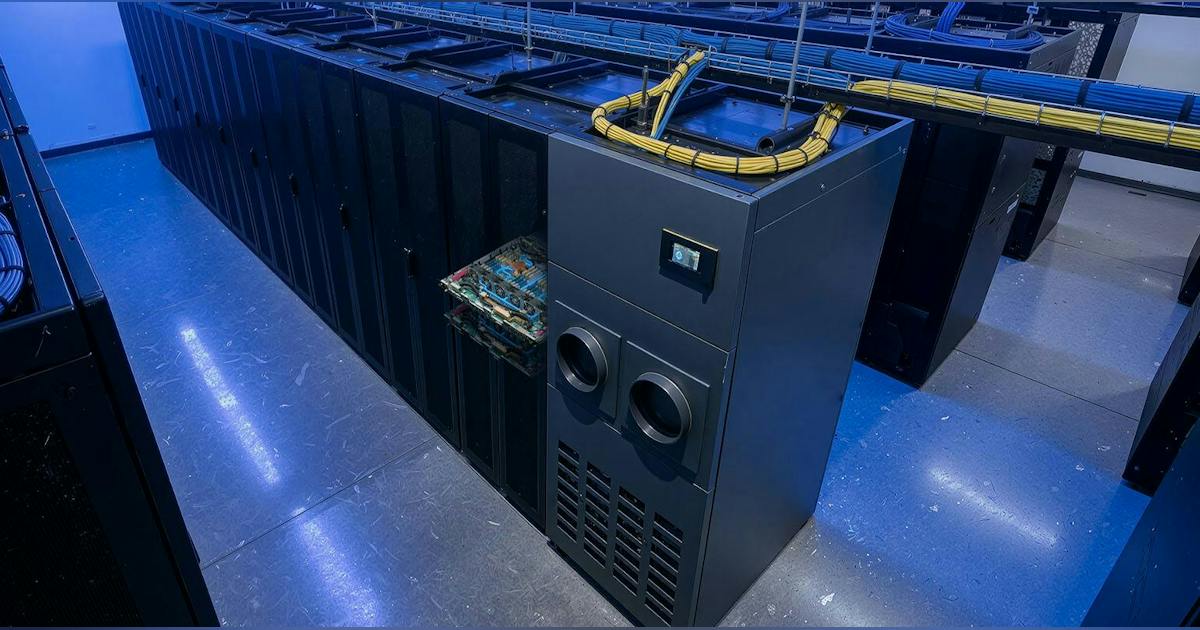
Neocloud providers are laser-focused on providing access to the newest and most powerful GPUs—often before hyperscalers can make them widely available. NVIDIA’s H100 and A100 accelerators, crucial for training and inference, are the cornerstone of these platforms. Many neoclouds go a step further, offering liquid-cooled racks, ultra-low-latency interconnects, and AI-specific storage tiers designed to keep pace with multi-petabyte datasets. For cutting-edge AI labs and fast-moving startups, this means the difference between weeks and months in development timelines.

2. Bare-Metal Performance

By eliminating the virtualization layers common in general-purpose clouds, neoclouds give users direct access to raw compute power. This bare-metal approach reduces latency and avoids the “noisy neighbor” problem, enabling highly deterministic performance—crucial when fine-tuning large language models or orchestrating tightly coupled GPU workloads. For teams pushing the edge of performance, every clock cycle matters, and neoclouds are delivering those cycles unfiltered.

3. Scalability on Demand

AI R&D is rarely linear. One month you’re iterating on small models, and the next you’re scaling to train a 70-billion-parameter transformer. Neocloud infrastructure is designed to expand and contract with those demands—supporting everything from a few nodes to full-scale superclusters. Unlike traditional clouds, which often impose capacity planning constraints or quotas, neoclouds thrive on elasticity, provisioning capacity dynamically and often within hours rather than weeks.

4. Cost Efficiency with Purpose-Built Pricing

Where hyperscalers often price GPU instances at a premium—factoring in legacy overhead and multi-tenant complexity—neoclouds keep things lean. Many operate with thinner margins and lower operational complexity, translating to significantly lower costs per training hour. Providers like Lambda, Run:ai, and Voltage Park offer transparent, workload-specific pricing that aligns with actual usage. High utilization rates and tailored provisioning models keep costs in check, making neoclouds especially appealing for startups and research groups running on grant cycles or VC runway.

These advantages make neoclouds invaluable not only for startups with limited budgets but also for established enterprises seeking to accelerate their AI initiatives.

Resilience at Scale: Why Neoclouds May Outlast the AI Hype Cycle

Investing in neoclouds offers a unique opportunity to participate in the AI boom without betting on specific applications or platforms. The rapid pace of innovation means that today’s leading AI models could be eclipsed by new breakthroughs tomorrow. However, regardless of which technologies prevail, the need for robust infrastructure will remain constant.

This dynamic mirrors historical gold rushes, where equipment suppliers thrived even as individual miners faced uncertainty. By providing essential tools for AI development, neocloud providers are positioned to benefit from sustained demand across diverse industries—from healthcare and finance to entertainment and logistics.

As the AI gold rush continues, neoclouds are poised to play an increasingly central role in shaping its trajectory. Their ability to deliver cost-effective, high-performance infrastructure makes them critical enablers of innovation. At the same time, their business model—focused on empowering others rather than competing directly—ensures they remain indispensable partners in the AI ecosystem.

Looking forward, neoclouds face challenges such as supply chain constraints for GPUs and competition from hyperscalers attempting to close the performance gap. However, their agility and specialization give them a distinct edge in navigating these hurdles. In many ways, they represent the future of cloud computing: leaner, faster, and more focused on solving specific problems.

As investors and enterprises seek ways to capitalize on AI’s transformative potential, neoclouds offer a compelling proposition—one that promises steady growth amid the chaos of rapid technological change.

Economic Disruption: How Neoclouds Are Redefining Cost and Performance

The emergence of neoclouds is causing a significant economic disruption in the AI infrastructure landscape. Unlike traditional hyperscalers that offer a broad range of services, neocloud providers concentrate on delivering optimized price-performance specifically for AI workloads. This specialization translates into several key advantages: higher GPU utilization rates, bare-metal access, and the application of deep, specialist expertise. These elements combine to create a compelling economic proposition for AI developers and enterprises.

The numbers speak for themselves. Neoclouds are achieving significant cost reductions, with reports from Uptime Institute indicating as much as 66% savings on GPU instances when compared to major hyperscalers. This substantial difference stems from the ability to maximize the use of expensive GPU resources and minimize overhead. For organizations running large-scale AI training or inference tasks, this can lead to considerable savings in operational expenses.

The efficiencies introduced by neoclouds are reshaping the overall economics of AI development. As models grow in complexity and require more compute power, the cost of training and deploying them has become a major barrier. By lowering these costs, neoclouds make it feasible for a wider array of organizations – from startups to established corporations – to engage in AI initiatives. This democratization of AI resources has the potential to accelerate innovation across diverse sectors, allowing more companies to harness the power of AI without breaking the bank.

Advancing Coopetition Between Neocloud Providers and Hyperscalers

The relationship between neocloud providers and traditional hyperscalers is increasingly defined by a complex blend of competition and collaboration. As the demand for AI infrastructure surges, both camps are vying for dominance in the lucrative GPU cloud market, yet their interactions are far from zero-sum, resulting in a competitive, yet symbiotic, market landscape.

Neoclouds have carved out a niche by specializing in GPU-accelerated infrastructure tailored for AI and machine learning workloads. Their agility, focus, and deep understanding of AI developers’ needs allow them to offer cost-effective, high-performance solutions that challenge the broader, premium-priced offerings of hyperscalers. While hyperscalers benefit from vast economies of scale and integrated ecosystems, their diversified business models and high-margin pricing strategies on their cloud businesses often result in higher prices for AI-specific resources.

Despite this competition, the two groups are increasingly intertwined. Neoclouds often position themselves not as direct competitors, but as complementary partners within enterprise multi-cloud strategies. For example, an organization might use a neocloud to train a large language model, then deploy it on a hyperscaler’s platform for inference and integration with other services. This approach allows enterprises to optimize for both performance and cost, leveraging the strengths of each provider.

Investment, Partnership, and Multi-Cloud Integration

The interplay between neoclouds and hyperscalers is further complicated by growing investment and partnership activity. Hyperscalers are not only competing with neoclouds but also investing in them and, in some cases, becoming their customers. A prominent example is Microsoft’s $10 billion commitment to CoreWeave to secure access to specialized GPU infrastructure through 2029. Such deals highlight the recognition by hyperscalers of the unique value neoclouds bring to the AI infrastructure ecosystem.

For enterprises, this dynamic is accelerating the adoption of multi-cloud strategies. By integrating neoclouds into their cloud portfolios, organizations can avoid vendor lock-in, optimize for specific workloads, and ensure access to scarce GPU resources. However, this also introduces new complexities, as enterprises must now manage interoperability and data movement across increasingly fragmented cloud environments.

Looking forward, the evolving relationship between neoclouds and hyperscalers increases the prospects (and pricing) of further M&A activity across key players. As neoclouds grow in scale and strategic importance, it is likely that some will be acquired by hyperscalers seeking to bolster their AI infrastructure capabilities and maintain competitive advantage. Such consolidation will reshape the market’s structure, potentially accelerating innovation through deeper integration, but also raising questions about pricing power and the pace of future disruption.

High Stakes Require High Investment

The capital intensity of neoclouds is staggering. Building and maintaining these specialized infrastructure platforms requires massive investments in GPUs, networking equipment, and data center facilities. To finance this expansion, neoclouds have tapped into both equity and debt markets, with some pioneering the use of GPU assets as collateral for loans. This approach allows them to leverage their hardware investments more efficiently, but also exposes them to the risk of depreciating GPU values and limited liquidity.

The market is also seeing large supply chain vulnerabilities, and rapid equipment obsolescence, increasing the risk of relying too heavily on any one provider. The rapid pace of innovation in chip design presents both opportunities and challenges. While new generations of GPUs promise increased performance and efficiency, they also render older hardware obsolete on extremely short timelines.

This creates a constant pressure to upgrade infrastructure, potentially straining finances and exacerbating supply chain vulnerabilities. Geopolitical factors and manufacturing bottlenecks can further disrupt the supply of GPUs, as we are seeing with recent tariffs affecting NVIDIA, thus impacting neocloud providers’ abilities to meet growing demand.

The Chipmaker Landscape: Navigating the Silicon Battleground of the Neocloud Era

The neocloud boom is redefining the data center ecosystem, driven by billions in venture capital and a red-hot GPU-backed debt market that’s rewriting the rules of infrastructure financing. But while the capital is flowing fast, the underlying hardware story is anything but straightforward. Supply chain constraints, hardware churn, and the specter of over-leverage hang over the sector as neocloud builders sprint to scale. At the heart of this high-stakes race sit the chipmakers — the true power brokers of the AI infrastructure gold rush.

NVIDIA holds the pole position, having effectively set the standard for AI compute with its high-performance GPUs and the proprietary CUDA software stack that developers now treat as foundational. The company’s dominance isn’t just about raw silicon; it’s about controlling the ecosystem. But as demand for AI infrastructure skyrockets, so do concerns about supply bottlenecks, pricing leverage, and the systemic risks of depending too heavily on a single vendor.

Enter AMD and Intel, both aggressively positioning themselves as viable alternatives. AMD’s Instinct accelerators have made meaningful headway, especially among hyperscalers and research labs looking for more open, programmable environments. Its embrace of open-source software and its tight integration across CPU and GPU workloads gives it an edge in environments where flexibility and long-term value matter.

Intel, meanwhile, is betting on a diversified portfolio and a vertically integrated approach. With CPUs, discrete GPUs, and dedicated AI accelerators (via Habana Labs), Intel is aiming to meet the market wherever the workload lands — from training massive models to powering real-time inference at the edge. Its growing software investments signal a deeper push to win developer mindshare, not just silicon sockets.

What’s increasingly clear is that chipmakers now play a strategic role that transcends component supply. Their influence touches everything from AI model optimization to deployment timelines and total cost of ownership. In a capital-intensive market where seconds of inference time and watts per rack can make or break a business model, silicon choices aren’t just technical — they’re existential.

For neocloud operators, the path forward demands architectural agility. Betting solely on NVIDIA may win short-term performance, but long-term resilience will require multi-vendor strategies that hedge against market shocks, broaden workload compatibility, and enhance buyer leverage. The most successful neocloud platforms will be those that understand chipmakers not just as suppliers, but as strategic partners — and occasionally, as competitive threats.

As the AI era matures, the chipmaker battleground will increasingly shape who wins the neocloud race — and who gets left behind in the silicon stampede.

Which Provides the Winning Competitive Edge: Specialization or Scale?

The rise of neoclouds has been driven by their ability to deliver specialized, high-performance infrastructure tailored for AI workloads. However, the question remains: are these advantages sustainable in the long term, or do they merely represent a transitional phase before hyperscalers catch up? For neoclouds to maintain a competitive edge, there are many potential scenarios to consider.

The Bull Case: Persistent Barriers to Entry

The argument for neoclouds’ long-term viability rests on several key factors:

Technical Complexity: Building and managing AI-optimized infrastructure requires deep expertise in GPU architecture, networking, and software. Neoclouds have cultivated this expertise over time, creating a barrier to entry that is difficult for hyperscalers to replicate quickly.

Specialization: Neoclouds focus solely on AI workloads, allowing them to optimize their infrastructure and services for the specific needs of AI developers. This specialization translates into superior performance and cost-efficiency compared to the more generalized offerings of hyperscalers.

Agility: Neoclouds tend to be smaller and more agile than hyperscalers, enabling them to adapt quickly to changing market conditions and emerging technologies. This agility is particularly valuable in the rapidly evolving field of AI.

The Bear Case: Margin Compression and Scale Advantages

Despite many advantages, neoclouds face significant challenges from hyperscalers:

Margin Compression: As hyperscalers invest more heavily in AI infrastructure and refine their offerings, they may be able to erode the price advantage currently enjoyed by neoclouds. Hyperscalers’ scale economies and ability to cross-subsidize AI services with other cloud offerings could put significant pressure on neocloud margins.

Scale Advantages: Hyperscalers possess massive economies of scale, allowing them to procure hardware at lower prices and invest more heavily in R&D. This scale advantage could enable them to leapfrog neoclouds in terms of performance and innovation.

Ecosystem Integration: Hyperscalers offer tightly integrated ecosystems of cloud services, making it easier for customers to build and deploy AI applications. Neoclouds may struggle to match this level of integration, particularly for enterprises that rely on a wide range of cloud services.

Scenarios for the Future

The future of the neocloud market is uncertain, but several scenarios are possible:

Coexistence: Neoclouds and hyperscalers coexist, with each catering to different segments of the market. Neoclouds focus on specialized AI workloads and customers who prioritize performance and cost-efficiency, while hyperscalers cater to enterprises seeking a broader range of cloud services and ecosystem integration.

Market Consolidation: Hyperscalers acquire leading neoclouds to bolster their AI infrastructure capabilities and gain access to specialized expertise. This scenario could lead to greater integration and innovation, but also raise concerns about pricing power and market competition.

Disruption: Neoclouds continue to innovate and disrupt the market, challenging the dominance of hyperscalers and attracting a growing share of AI workloads. This scenario would require neoclouds to overcome challenges related to scale, ecosystem integration, and capital access.

Ultimately, the long-term success of neoclouds will depend on their ability to differentiate themselves from hyperscalers, innovate continuously, and adapt to the rapidly evolving needs of the AI community.

Making AI More Accessible: Who’s Using Neoclouds—and Why It Matters

The neocloud market represents a dynamic and essential force driving innovation in the age of AI. By specializing in high-performance, cost-effective infrastructure, neocloud providers are not only enabling the AI revolution, but also reshaping the economics of cloud computing.

Whether as “picks and shovels” suppliers to the AI gold rush, or as competitive partners alongside hyperscalers, neoclouds are proving their enduring value in a rapidly evolving technological landscape. And as they navigate the challenges of scale, financing, and chipmaker dependencies, the neoclouds are poised to continue pushing the boundaries of what’s possible in AI, fostering a more accessible and innovative future for all.
Shape
Shape
Stay Ahead

Explore More Insights

Stay ahead with more perspectives on cutting-edge power, infrastructure, energy,  bitcoin and AI solutions. Explore these articles to uncover strategies and insights shaping the future of industries.

Shape

CoreWeave brings Nvidia Vera Rubin, AI tools to its cloud services

Forge brings together experiment tracking, evaluation, agent observability, post-training, inference and model management. The platform is designed to let teams use their preferred models, frameworks and cloud environments rather than locking them into a single AI stack, CoreWeave stated. The company described Forge as a continuous AI development loop in

Read More »

Canada lists Pacific Link as Project of National Interest

The Government of Canada on Oct. 1 listed the Pacific Link project as a Project of National Interest under the Building Canada Act, advancing work to secure permissions needed to begin pipeline design and construction as early as Sept. 1, 2027. Pacific Link, formerly known as the West Coast oil pipeline, is a proposed 1 million-b/d crude oil pipeline that would transport Alberta oil to Canada’s west coast for export to Asia-Pacific and other global markets. With the Project of National Interest designation, Pembina Pipeline Corp., Calgary, along with the Governments of Alberta and Canada, and Trans Mountain Corp., will advance the project under a streamlined regulatory review process. Pembina said the listing “provides greater certainty through a clearer, more efficient and predictable federal review process that will maintain environmental standards and Indigenous consultation, which will be led by the Major Projects Office and supported by the Canada Energy Regulator.” Trans Mountain Corp. is responsible for the regulatory process, stakeholder and Indigenous engagement, construction of the project, and subsequent operation of the asset. Pembina’s economic interest through construction will be 10%, with the opportunity to acquire up to an additional 10% once the project enters commercial operation.

Read More »

Chevron ups interest in Namibia license with drill-ready prospect

Harmattan Energy Ltd., an affiliate of Chevron Corp., has agreed to a deal with Custos Energy (Pty) Ltd. subsidiary Trago Energy (Pty) Ltd. for interest in Petroleum Exploration License 90 (PEL 90) offshore Namibia.   Under the agreement, Trago will transfer all of its participating interest (10%) in PEL 90 in Namibia’s Orange Basin to license-operator Chevron, in exchange for $11 million in cash at completion. Further contingent consideration is payable on achievement of appraisal and production milestones, including revenues associated with commercial production currently estimated at 1.5-2.5 million bbl of oil (dependent upon commodity price assumptions), Custos said. With the deal, Chevron adds interests that help offset a famout deal entered into with Equinor.  In August, the operator agreed to divest to Equinor a 17.4% portion of its interest in the license, which contains a drill-ready prospect—Nabba-1X—slated for drilling before yearend. The well is part of a broader multi-well exploration program planned by Chevron across Sub-Saharan Africa. Nabba-1X will be Chevron’s second well offshore Namibia following Kapana-1X, where the company gathered geological data but did not encounter commercial hydrocarbons. Completion of Trago Energy’s farm-out to Chevron is conditional upon various governmental, regulatory, and third-party approvals.

Read More »

Trump cites $54 billion South Korean plan for Alaska LNG

US President Donald Trump on Sept. 30 said South Korea plans to invest $54 billion in the long-delayed Alaska LNG project as part of a broader package of up to $200 billion in South Korean investment in US energy projects. The announcement does not represent a final investment commitment. South Korean officials said the two countries agreed only to review the project’s commercial viability. South Korea separately finalized a $22.3-billion investment in a 6.47-Gw gas-fired power plant in Encinal, Tex., that would supply electricity to an adjacent AI data center campus. Proposed participation in Alaska LNG and a separate framework involving eight US nuclear reactors remain subject to feasibility reviews. The Alaska LNG project would transport North Slope gas through an 807-mile pipeline to a liquefaction and LNG export terminal at Nikiski on the Kenai Peninsula. Designed capacity is up to 20 million tpy of LNG, primarily for Asian markets. Glenfarne Group is lead developer and majority owner, holding a 75% stake acquired in 2025 from Alaska Gasline Development Corp. (AGDC), which retained 25%. The project originated in 2014 as a joint effort between AGDC, ExxonMobil, ConocoPhillips, bp, and TransCanada. After the producers withdrew, AGDC became sole owner in 2017 until Glenfarne assumed control. FERC approved the project in 2020, and federal permitting was completed in 2025. A final investment decision (FID), however, has been delayed by high capital costs and the need to secure sufficient LNG offtake commitments. Glenfarne has preliminary agreements covering about 13 million tpy and has said roughly 16 million tpy is needed to support financing. The company plans to develop Alaska LNG in two financially independent phases. The first would build a pipeline supplying North Slope gas to Alaska consumers, while the second would add LNG export infrastructure. Glenfarne is targeting a pipeline investment decision

Read More »

Matador outlines drilling plans with Paloma acquisition now closed

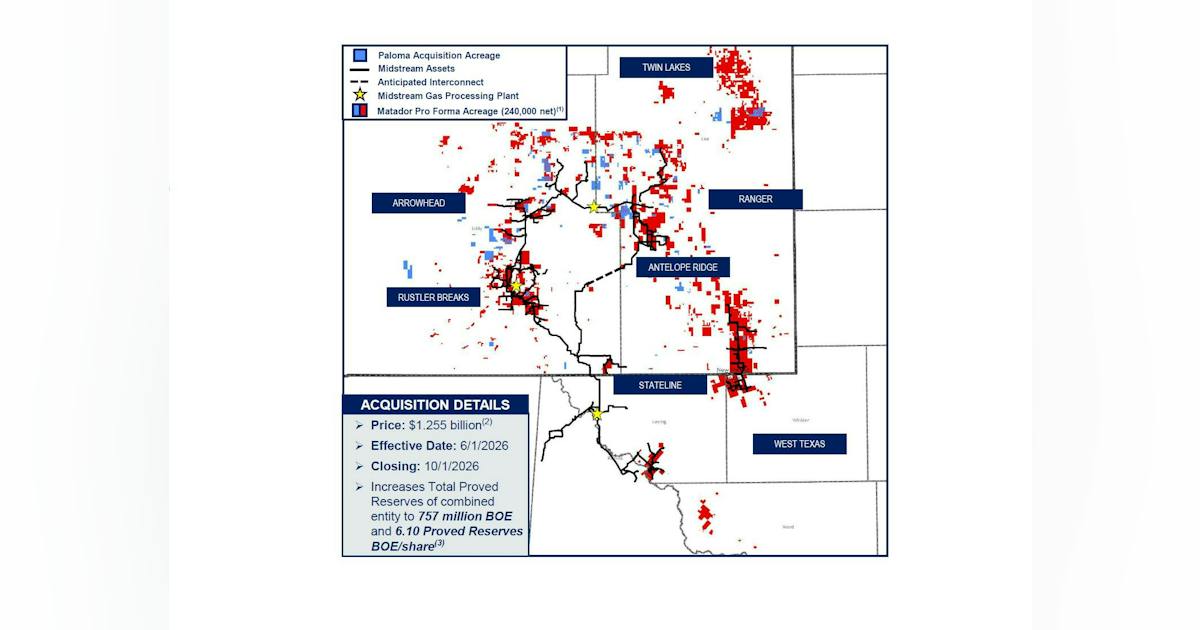
The acquired position includes about 16,500 net acres in Eddy and Lea counties, NM, most of which is held by production, along with more than 156 future drilling locations (normalized to 2-mile laterals) across nine or more prospective benches. Matador said 59 drilling permits have already been approved on the Delaware basin acreage. The company said assets associated with the acquisition are producing an estimated 12,200 boe/d in the third quarter, about 55% of which is oil. Matador added that production from the acquired properties has exceeded underwriting estimates by roughly 10% since June 1, largely due to strong performance from recently drilled wells in Eddy County. According to company materials, the acquisition adds an estimated 55 MMboe of proved reserves, 67% of which is oil, with a PV-10 value of about $816 million.  Matador said the Paloma acquisition, together with its pending acquisition of Ridge Runner Resources II LLC acreage and acreage added in the May 2026 federal lease sale, is expected to increase its Delaware basin position to about 240,000 net acres in fourth-quarter 2026, nearly 20% above its October 2025 acreage position. Chairman and chief executive officer Joseph Wm. Foran said the acquired acreage holds some of the highest hydrocarbon resources per acre in the Lower 48 and is expected to provide opportunities for upstream and midstream value creation as it is integrated into its wholly-owned midstream system and its 51%-owned San Mateo Midstream system.

Read More »

Energy Department Announces Up to $400 Million for Basic Research to Advance the Frontiers of Science

WASHINGTON—The U.S. Department of Energy (DOE) today announced its annual funding opportunity of up to $400 million to advance the frontiers of scientific knowledge and lay the foundation for future technologies and innovation. The funding delivers on President Trump’s Executive Order Restoring Gold Standard Science by supporting rigorous, transparent, and mission-driven research across DOE’s Office of Science to strengthen America’s scientific and technological leadership. “Foundational research is where the breakthroughs that shape America’s future begin,” said DOE Under Secretary for Science Darío Gil. “Through this investment, we are empowering our nation’s researchers to pursue bold ideas, push the boundaries of discovery, and build the scientific foundations for tomorrow’s technologies—strengthening America’s global leadership in science and innovation.” The funding will support research across DOE’s Office of Science and its major programs to tackle some of the nation’s greatest scientific challenges and accelerate discoveries in areas critical to America’s future. Research will span Advanced Scientific Computing Research, Basic Energy Sciences, Biological and Environmental Research, Fusion Energy Sciences, High Energy Physics, Nuclear Physics, and Isotope R&D and Production. The Notice of Funding Opportunity (NOFO), informally known as the “Open Call,” is issued annually at the beginning of each Fiscal Year (FY). It provides a vehicle for DOE’s Office of Science to solicit applications from institutions for research support in areas not covered by more specific, topical NOFOs issued by the office in FY 2027. More details about this Notice of Funding Opportunity can be found here. DOE’s Office of Science is the nation’s largest supporter of basic research in the physical sciences, funds research at hundreds of universities nationwide, and stewards 10 of DOE’s National Laboratories.

Read More »

Magnolia sells non-core South Texas assets, adds Karnes-area acreage during WildFire integration

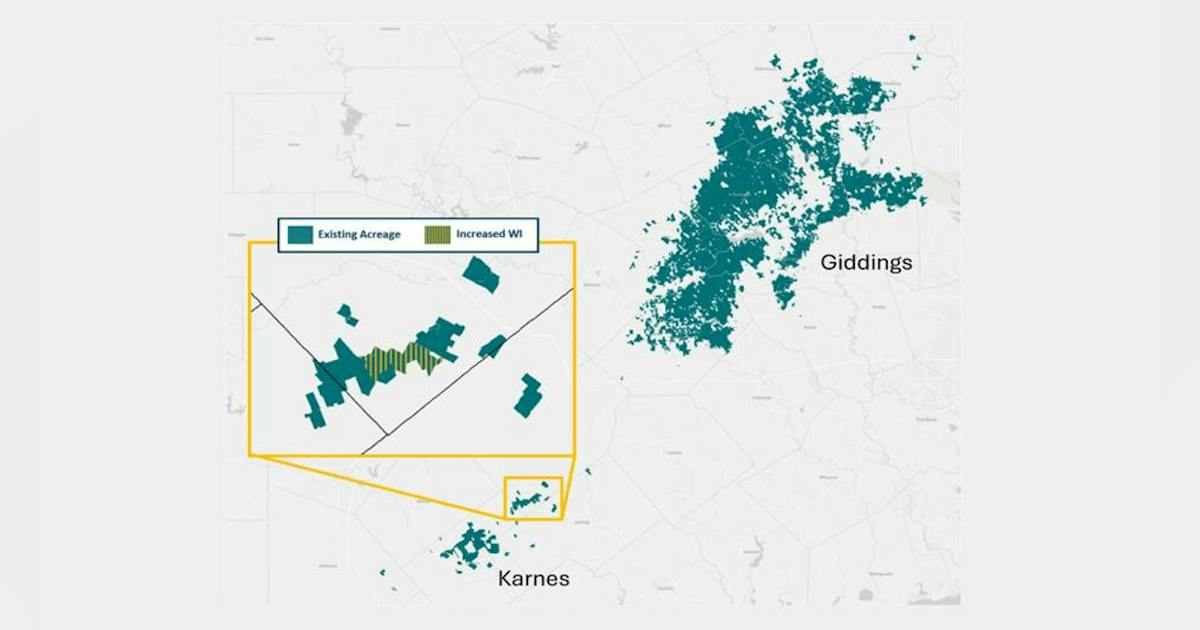
The company disclosed the transaction as part of an operational update following the recent closing of its acquisition of WildFire Energy. Chris Stavros, Magnolia chairman, president, and chief executive officer, said integration of the WildFire assets is progressing as planned as the company works to build a larger Eagle Ford and Austin Chalk position across South Texas. Production, capital outlook Third-quarter 2026 production is expected to average 116,000-118,000 boe/d (about 42% oil), reflecting the WildFire acquisition and the impact of the divested properties, Magnolia said. Drilling and completion (D&C) capital spending for the quarter is expected to total $155-165 million. For fourth-quarter 2026, the first full quarter reflecting the WildFire acquisition, production is forecast at 159,000-161,000 boe/d with oil accounting for 49-50% of volumes. D&C spending is expected to be about $235 million. For 2027, Magnolia expects both oil production and total production to grow 4-5% from a second-quarter 2026 pro forma base of about 78,000 bo/d and 158,000 boe/d, respectively, after accounting for volumes associated with the asset sale. The company currently estimates 2027 D&C capital spending of $900-950 million, including the impact of modest oilfield service cost inflation.

Read More »

Startup doxx.net hands the network controls to AI

“The whole thing is run completely by AI, so behind the scenes, I mean, it’s a network with 31 locations around the world, and internally there’s a mesh network, and I can’t, as a human being, manage all of this by myself,” Lyon said. Lyon said the team modeled every site, down to the wire and the optic, in a virtual model before building. An infrastructure management system running the company’s own AI on its own hardware then ordered the installation. It orchestrated shipping and delivery through data center APIs. Human technicians performed the remote smart hands installations. The company also built tools for agents to work with users and with the network. An agent gateway gives an AI agent an identity in the doxx.net chat app. The user pastes a credential into the agent. The agent obtains its certificate and appears in the user’s chat. Users can create group chats with several agents. In one example, Lyon said one agent runs BGP while others handle other tasks.

Read More »

DCF Poll: What Must Data Centers Prove to Keep Building at AI Scale?

For years, the data center industry’s biggest constraints were largely physical, centered on power, transmission, land, water, equipment and labor. As the AI infrastructure buildout accelerates, however, another constraint is moving rapidly to the foreground. The constraint, and the concern, is whether host communities, regulators and policymakers believe the next generation of data centers is being built on terms that work for them, too. That question received a fresh exclamation point on Oct. 2, when Amazon Web Services announced it will invest more than $1 billion over five years in U.S. communities where it operates data centers, with funding aimed at areas including energy affordability, water and natural-resource protection, workforce development and education. The initiative arrives as electricity and water consumption associated with hyperscale infrastructure faces increasing scrutiny in communities across the country. And AWS is responding to a policy environment that is changing quickly. In Virginia, Loudoun County supervisors have begun a process that could pause action on certain new data center and substation applications for as long as 12 months while the county reviews its development policies. The board is scheduled to consider the proposed pause Oct. 20. Just next door, Prince William County voted Sept. 22 to dramatically shrink the area where data centers can be developed by right, largely shifting future projects outside the revised overlay into a case-by-case special-use permitting process. The issue is spreading well beyond Northern Virginia. On Sept. 23, Maryland Gov. Wes Moore signed an executive order creating a statewide framework for data center development centered on ratepayer protection, environmental impacts, community participation, transparency and accountability. Meanwhile, the U.S. House on Sept. 16 passed the Ratepayer Protection Act by a 417–3 vote, seeking to prevent data centers and other large loads from shifting the incremental costs of new generation and grid infrastructure onto

Read More »

$6T in annual AI revenue needed to pay off data center investments

Making the assumption that hyperscalers’ capital expenditure amounts to about 25% of revenue, they would need the AI market to be worth $6 trillion annually. But, said Bain, the current consumer and enterprise AI markets together could be worth up to $1.8 trillion by 2031, leaving a whopping $4.2 trillion still to find from new markets. Bain highlighted four potential areas: the use of AI in search; the development of more autonomous vehicles, including drones; physical AI, including digital twins and robotics; and new product development, for example, breakthroughs in pharmaceuticals.

Read More »

HPE’s Rahim: Pace of change in the data center is ‘extraordinary’

Network protection: As networking and security converge, Rahim said HPE continues to embed security throughout the network by combining SASE, network access control, firewalls, identity-based policy enforcement, and AI-powered operations. HPE’s security revenue is expected to grow at a high-single-digit percent CAGR through fiscal 2029. Partners: On Nov. 1, HPE will converge the Juniper and Aruba programs under one unified partner program, HPE Partner Ready Vantage. “Partners drive most of our networking business, and this milestone will enable all 60,000 HPE partners to sell the full networking portfolio through one unified partner program. Before the acquisition, only around 10% of HPE Aruba Networking and Juniper partners overlapped, and so this creates a significant cross-selling opportunity as we bring the combined HPE Networking portfolio to a much broader set of sellers and customers.” Service growth: “Today, services represent about one-third of our HPE Networking business. Services deepen customer relationships, add higher margin recurring revenue, and improve the quality of our products driving durable earnings,” Rahim said. HPE sees an opportunity to bring that business model and the culture to Aruba across a much larger installed base. “So, by fiscal 2028, we expect to increase services attach rates by five percentage points, supporting both recurring revenue growth and margin expansion,” Rahim said.

Read More »

Data Center Private Power: Who Regulates Behind-the-Meter Generation?

The Cases Writing the Rules The regulatory questions surrounding private power are no longer theoretical. Federal regulators, regional grid operators and state utility commissions are already confronting disputes over co-located generation, transmission obligations, large-load tariffs and the financial commitments required from data center customers. Amazon–Talen Puts Co-Location Before FERC The Amazon–Talen–Susquehanna dispute became the most prominent federal test of how far a co-located data center can separate its power supply from the regional grid while remaining connected to the grid’s reliability framework. Amazon Web Services operates a data center campus adjacent to Talen Energy’s Susquehanna nuclear plant in Pennsylvania. In 2024, the parties sought to expand the co-located load from 300 MW to 480 MW through an amended interconnection agreement with PJM. The proposed structure would have allowed the campus to receive more power directly from the nuclear plant while reducing the plant’s capacity interconnection rights on the PJM system. FERC rejected the amendment in November 2024, concluding that PJM had not justified the nonstandard provisions in the agreement. Importantly, the Commission did not prohibit co-location or dedicated generation. The dispute instead exposed a larger gap in existing transmission rules: how should a large load located beside a generator be measured, what transmission service does it require, what happens when the generator is unavailable, and how should the project pay for continued access to regional reliability? Those questions soon moved beyond the Amazon–Talen project itself. In December 2025, FERC found that PJM’s existing framework did not provide sufficiently clear and consistent rules for generators serving co-located loads or for transmission customers taking service on their behalf. The Commission directed PJM to develop defined interconnection and operating requirements along with transmission options ranging from conventional network service to firm and non-firm contract-demand structures. The central issue is deceptively simple: physical proximity

Read More »

Data Center Thermal Management Series-Part 1 of 3

The biggest driver in today’s global economy is the data center, and in the process, data centers are generating and taking more heat than ever before. Heat — the generation of it and public concerns about it — is the most pressing issue facing the data center industry. In response, data center managers and engineers are viewing the problem in new ways, devising innovative, next-generation thermal control strategies that manage the problem more effectively. In the minds of IT managers and the public, data centers and AI are joined at the hip, along with increasing power demands and associated issues of environmental impact, water usage, and higher utility costs. As community activists, political leaders, and now even some prominent AI industry CEOs call for limits on AI development and data center construction, it’s imperative that the data center industry better manage the heat they’re producing — and taking. Sponsored Resources: Texas Instruments’ portfolio of data center thermal management systems spans the full coolant path. It’s been under active development at TI for decades and has evolved in response to the rising power, computing demands, and complexity of advanced data centers. Traditional thermal management techniques can’t keep up with AI’s intense computing requirements. For decades, air cooling was sufficient. Fans blew cool air across hot components and carried heat away, keeping data centers and AI servers operating reliably. But with AI training and inference pushing rack power beyond 20kW to 40kW, air alone can no longer remove heat quickly enough. In addition, air cooling is noisy and consumes too much energy. AI server racks are coming online now that draw 100kW of power, and they’re on their way to more than a megawatt in a few years. Each generation of servers grows denser, more powerful, and hotter as they move and compute massive volumes

Read More »

Microsoft will invest $80B in AI data centers in fiscal 2025

And Microsoft isn’t the only one that is ramping up its investments into AI-enabled data centers. Rival cloud service providers are all investing in either upgrading or opening new data centers to capture a larger chunk of business from developers and users of large language models (LLMs).  In a report published in October 2024, Bloomberg Intelligence estimated that demand for generative AI would push Microsoft, AWS, Google, Oracle, Meta, and Apple would between them devote $200 billion to capex in 2025, up from $110 billion in 2023. Microsoft is one of the biggest spenders, followed closely by Google and AWS, Bloomberg Intelligence said. Its estimate of Microsoft’s capital spending on AI, at $62.4 billion for calendar 2025, is lower than Smith’s claim that the company will invest $80 billion in the fiscal year to June 30, 2025. Both figures, though, are way higher than Microsoft’s 2020 capital expenditure of “just” $17.6 billion. The majority of the increased spending is tied to cloud services and the expansion of AI infrastructure needed to provide compute capacity for OpenAI workloads. Separately, last October Amazon CEO Andy Jassy said his company planned total capex spend of $75 billion in 2024 and even more in 2025, with much of it going to AWS, its cloud computing division.

Read More »

John Deere unveils more autonomous farm machines to address skill labor shortage

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More Self-driving tractors might be the path to self-driving cars. John Deere has revealed a new line of autonomous machines and tech across agriculture, construction and commercial landscaping. The Moline, Illinois-based John Deere has been in business for 187 years, yet it’s been a regular as a non-tech company showing off technology at the big tech trade show in Las Vegas and is back at CES 2025 with more autonomous tractors and other vehicles. This is not something we usually cover, but John Deere has a lot of data that is interesting in the big picture of tech. The message from the company is that there aren’t enough skilled farm laborers to do the work that its customers need. It’s been a challenge for most of the last two decades, said Jahmy Hindman, CTO at John Deere, in a briefing. Much of the tech will come this fall and after that. He noted that the average farmer in the U.S. is over 58 and works 12 to 18 hours a day to grow food for us. And he said the American Farm Bureau Federation estimates there are roughly 2.4 million farm jobs that need to be filled annually; and the agricultural work force continues to shrink. (This is my hint to the anti-immigration crowd). John Deere’s autonomous 9RX Tractor. Farmers can oversee it using an app. While each of these industries experiences their own set of challenges, a commonality across all is skilled labor availability. In construction, about 80% percent of contractors struggle to find skilled labor. And in commercial landscaping, 86% of landscaping business owners can’t find labor to fill open positions, he said. “They have to figure out how to do

Read More »

2025 playbook for enterprise AI success, from agents to evals

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More 2025 is poised to be a pivotal year for enterprise AI. The past year has seen rapid innovation, and this year will see the same. This has made it more critical than ever to revisit your AI strategy to stay competitive and create value for your customers. From scaling AI agents to optimizing costs, here are the five critical areas enterprises should prioritize for their AI strategy this year. 1. Agents: the next generation of automation AI agents are no longer theoretical. In 2025, they’re indispensable tools for enterprises looking to streamline operations and enhance customer interactions. Unlike traditional software, agents powered by large language models (LLMs) can make nuanced decisions, navigate complex multi-step tasks, and integrate seamlessly with tools and APIs. At the start of 2024, agents were not ready for prime time, making frustrating mistakes like hallucinating URLs. They started getting better as frontier large language models themselves improved. “Let me put it this way,” said Sam Witteveen, cofounder of Red Dragon, a company that develops agents for companies, and that recently reviewed the 48 agents it built last year. “Interestingly, the ones that we built at the start of the year, a lot of those worked way better at the end of the year just because the models got better.” Witteveen shared this in the video podcast we filmed to discuss these five big trends in detail. Models are getting better and hallucinating less, and they’re also being trained to do agentic tasks. Another feature that the model providers are researching is a way to use the LLM as a judge, and as models get cheaper (something we’ll cover below), companies can use three or more models to

Read More »

OpenAI’s red teaming innovations define new essentials for security leaders in the AI era

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More OpenAI has taken a more aggressive approach to red teaming than its AI competitors, demonstrating its security teams’ advanced capabilities in two areas: multi-step reinforcement and external red teaming. OpenAI recently released two papers that set a new competitive standard for improving the quality, reliability and safety of AI models in these two techniques and more. The first paper, “OpenAI’s Approach to External Red Teaming for AI Models and Systems,” reports that specialized teams outside the company have proven effective in uncovering vulnerabilities that might otherwise have made it into a released model because in-house testing techniques may have missed them. In the second paper, “Diverse and Effective Red Teaming with Auto-Generated Rewards and Multi-Step Reinforcement Learning,” OpenAI introduces an automated framework that relies on iterative reinforcement learning to generate a broad spectrum of novel, wide-ranging attacks. Going all-in on red teaming pays practical, competitive dividends It’s encouraging to see competitive intensity in red teaming growing among AI companies. When Anthropic released its AI red team guidelines in June of last year, it joined AI providers including Google, Microsoft, Nvidia, OpenAI, and even the U.S.’s National Institute of Standards and Technology (NIST), which all had released red teaming frameworks. Investing heavily in red teaming yields tangible benefits for security leaders in any organization. OpenAI’s paper on external red teaming provides a detailed analysis of how the company strives to create specialized external teams that include cybersecurity and subject matter experts. The goal is to see if knowledgeable external teams can defeat models’ security perimeters and find gaps in their security, biases and controls that prompt-based testing couldn’t find. What makes OpenAI’s recent papers noteworthy is how well they define using human-in-the-middle

Read More »