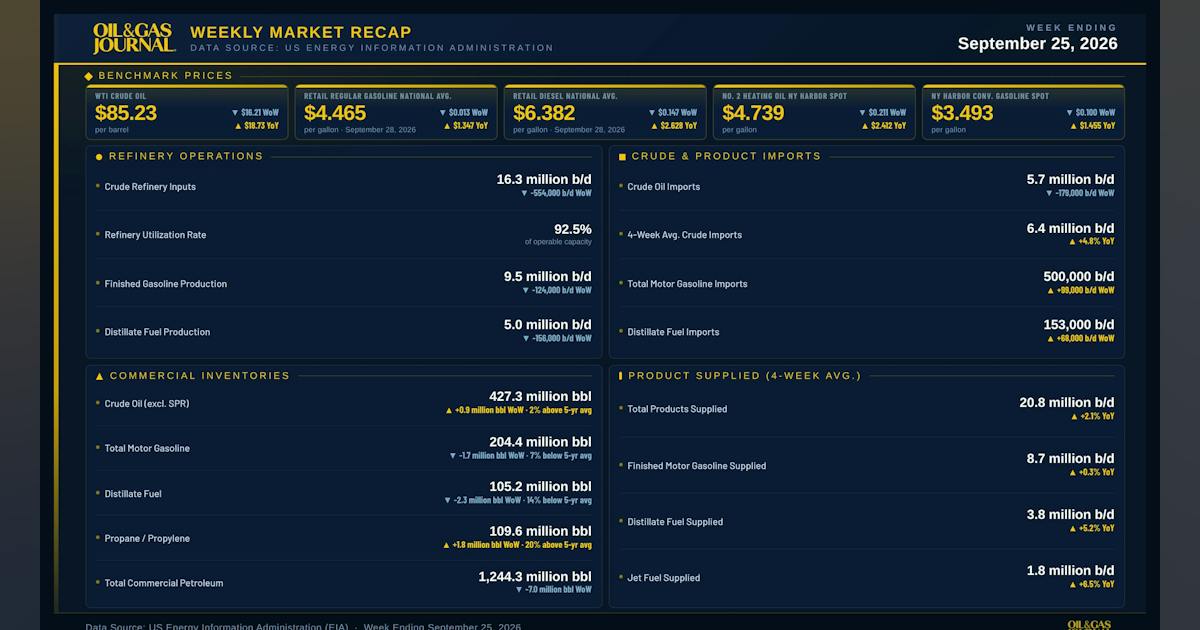
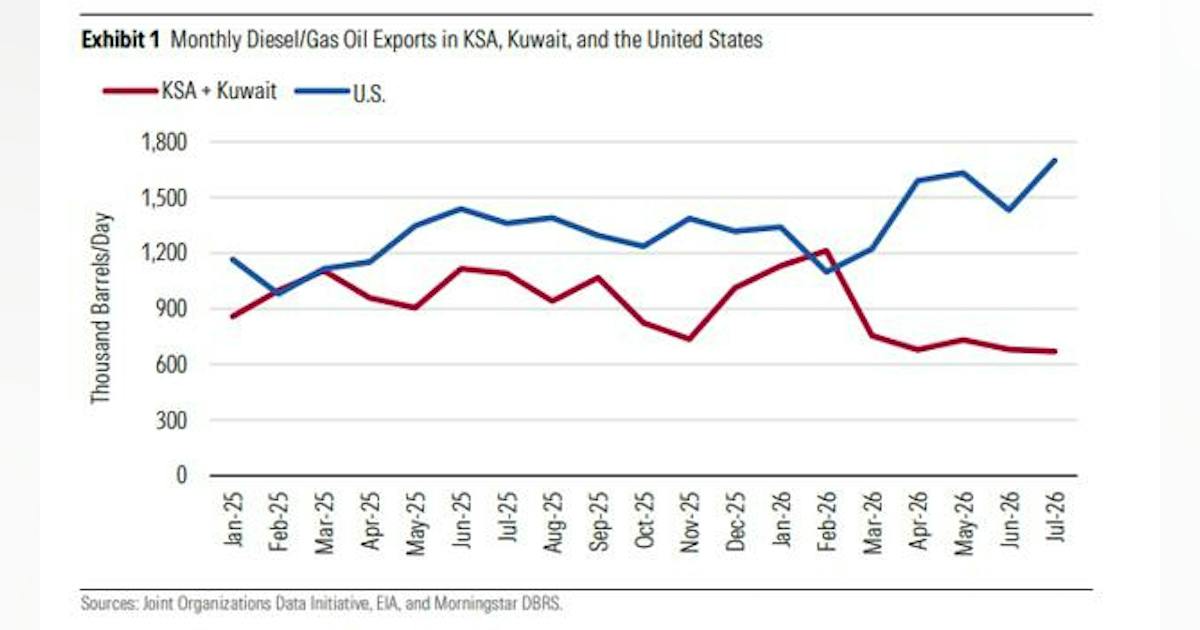
US refiners are benefiting from a tightening global diesel market as disruptions in the Middle East and Russia constrain supply, lift crack spreads, and keep refinery utilization near capacity, according to Morningstar DBRS. Morningstar DBRS said the current market is creating a strong but likely temporary earnings and cash-flow tailwind for US refiners. High utilization, low inventories, and elevated diesel margins are supporting operating cash flow and EBITDA, although the benefit could fade if geopolitical disruptions ease. Global diesel supply has tightened since the start of the Iran war as refinery outages, lower crude runs, and constraints on product exports through the Strait of Hormuz reduced Middle East supply. Saudi Arabia and Kuwait diesel exports were down about 40% year over year in July. Russia, meanwhile, extended restrictions on most diesel exports into October. Russia exported more than 780,000 b/d of diesel in 2025, just under 10% of global exports. US refiners have increased output and exports to help fill the gap. Distillate production averaged 5.1 million b/d during January-August, the highest since 2019. Refinery utilization is already near capacity in several regions, leaving limited room for further increases in output. PADDs 2 and 4 are operating at or near capacity, supported by discounted Canadian crude, strong diesel export demand, and agricultural and rural consumption. Together, the two regions account for more than 27% of US refining capacity and have an average distillate yield of 32%, DBRS said. On the Gulf Coast, PADD 3 refinery utilization exceeded 98% in September. More than half of US refining capacity is concentrated in PADD 3, where complex refineries serve both export markets and other US regions. The stronger operating environment is translating into higher refining margins. The US Gulf Coast ultra-low-sulfur diesel premium over crude has risen to its highest level this year,