Stay Ahead, Stay ONMINE

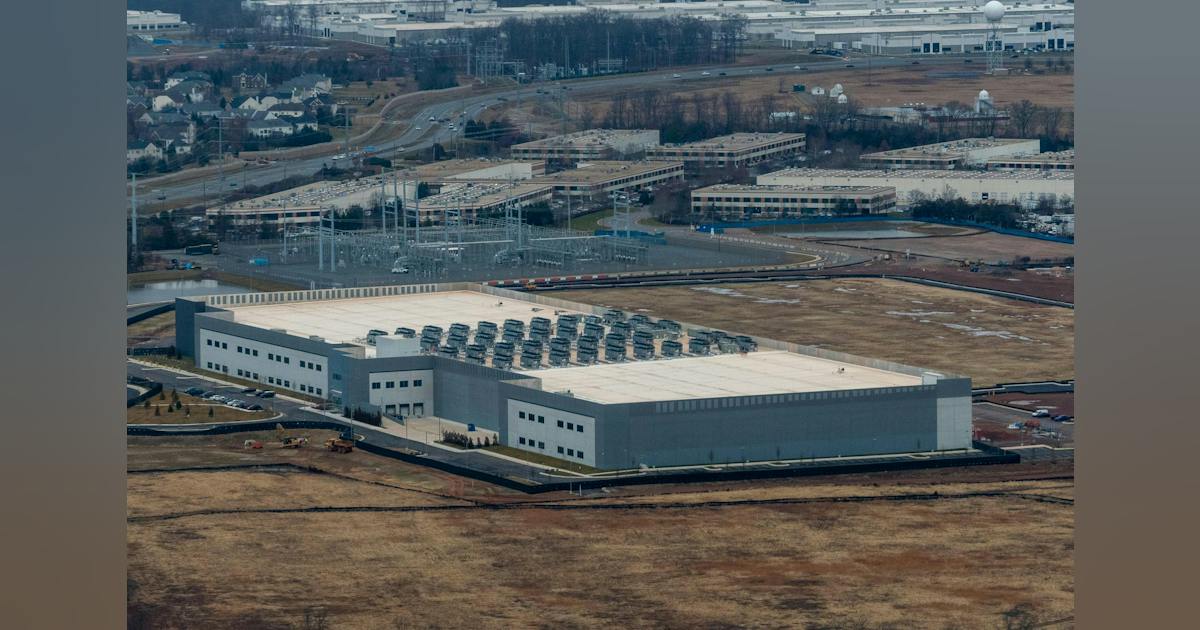
Virginia’s New Data Center Bargain: Power, Permits and the Right to Build

What Took Effect—and What Still Requires Legislation Spanberger laid out the administration’s rationale in announcing the framework: “In the years before I took office, data centers came to Virginia and the Commonwealth did not have a clear or coordinated plan to address their impacts on Virginians — on their electric bills, their water, their land, […]

What Took Effect—and What Still Requires Legislation

Spanberger laid out the administration’s rationale in announcing the framework:

“In the years before I took office, data centers came to Virginia and the Commonwealth did not have a clear or coordinated plan to address their impacts on Virginians — on their electric bills, their water, their land, their air, or their quality of life. That changes today. I have said many times that Virginia should be leading the nation in setting the highest standards for this industry. And now, I believe we are doing just that.”

The distinction between what Virginia has already implemented and what the administration intends to pursue is consequential. Executive Order 22 establishes immediate directives for state agencies, while significant portions of the broader Data Center Accountability Framework remain proposals for the 2027 General Assembly or future regulatory action.

Among the immediate changes, executive-branch agencies are prohibited from entering into or enforcing new nondisclosure agreements that conceal material information about proposed commercial data centers, public incentives, resource demands or community impacts. Existing contractual commitments are preserved, with limited exceptions contemplated for extraordinary circumstances, including national security. The prohibition does not yet extend automatically to local governments.

The order also excludes new data center projects with anticipated peak electrical demand of 25 MW or greater from the Virginia Business Ready Sites Program and similar discretionary state site-readiness and expedited-review assistance.

A separate, potentially more consequential proposal would eliminate by-right development approval for data centers using more than 25 MW, requiring local approval even for projects with prior authorizations. That provision has not been enacted statewide and could introduce significant legal questions concerning established development rights.

The administration is also accelerating environmental oversight. Within 120 days of the order, the Office of the Chief Energy Officer must publish an initial Data Center Planning and Community Engagement Toolkit to help localities evaluate proposed facilities, assess infrastructure and environmental impacts, and negotiate community-benefit agreements.

The Department of Environmental Quality has 180 days to produce accelerated rulemaking plans addressing data center noise and cooling-water scarcity, along with findings and recommendations concerning the cumulative impacts of diesel and other backup generation. The order specifically directs designation of the Eastern Virginia Groundwater Management Area as a cooling-water-scarcity area, although the associated regulatory process remains underway.

Virginia Energy, meanwhile, must evaluate opportunities for lower-impact development, including brownfield redevelopment, adaptive reuse, smaller distributed facilities and sites where infrastructure capacity already exists. Its recommendations are due within 240 days.

The order also initiates development of Virginia Local Energy and Accountable Data Centers, or VA-LEAD, a proposed tiered designation system modeled on resource-efficiency programs such as LEED. Facilities would be evaluated on energy and infrastructure impacts, water and land use, noise, workforce development, clean-energy investments and community benefits.

Once established, VA-LEAD is intended to help state agencies prioritize incentives and administrative assistance for higher-performing projects. Proposed criteria and an implementation plan are due by the end of 2027.

Taken together, the measures establish a regulatory direction that is considerably more expansive than the requirements currently in force. For developers, the immediate changes matter. But the greater uncertainty lies in how Virginia’s proposed standards will ultimately be translated into enforceable requirements governing land use, infrastructure investment and access to electricity.

The New Cost of Power and Development Risk

Virginia developers have traditionally been able to assemble some projects sequentially: secure land, establish zoning rights, pursue utility service, identify a customer and then work through the infrastructure requirements necessary to deliver power.

That model becomes considerably more difficult when developers face greater public disclosure, fewer by-right development pathways, stronger financial commitments to utilities and the prospect of paying more directly for the transmission and generation infrastructure their projects require.

But the changing economics of Virginia data center development did not begin with Spanberger’s September announcement. Regulators were already moving to assign more of the financial risk associated with large electrical loads to the customers creating that demand.

In November 2025, the Virginia State Corporation Commission approved a new GS-5 rate class for large electricity customers, including data centers, with demand of at least 25 MW on a contiguous site and a measured or expected load factor of at least 75%.

As DCF previously reported, beginning January 1, 2027, new qualifying customers face minimum 14-year service commitments. Applicable minimum billing requirements include 85% of contracted transmission and distribution demand and 60% of generation demand, subject to specified exemptions. The rules are intended to prevent the costs of infrastructure built for large customers from falling disproportionately on other utility ratepayers if anticipated demand fails to materialize.

The SCC has also approved a framework for directly assigning the costs of dedicated transmission connections to new or expanding large-load customers when those facilities would not otherwise be needed. Implementation details remain subject to further proceedings.

Virginia has added another financial consideration through a statewide data center electricity consumption tax that took effect July 1, 2026. Set at 1.1 cents per kilowatt-hour, the tax applies to qualifying data center electricity consumption, including power generated onsite rather than purchased from a utility. The current budget provision runs through June 2028 and includes a mechanism to refund annual collections exceeding $600 million.

These measures add financial consequences to projects that secure large power allocations but fail to reach their projected operating capacity. They also make the credibility of future electricity demand increasingly consequential to the economics of development.

The scale of that prospective demand is extraordinary.

In its July 2026 earnings presentation, Dominion Energy Virginia reported approximately 53.8 GW of data center capacity in various stages of contracting, up roughly 11% from the end of 2025. But only about 12 GW of that total was covered by electric service agreements. The remainder consisted of projects at earlier engineering and construction-authorization stages, underscoring the difference between a utility’s contracted development pipeline and demand that is firmly committed, much less already operating.

Data centers accounted for 28% of Virginia Power’s electricity sales in 2025, up from 26% the previous year. A 2024 analysis by Virginia’s Joint Legislative Audit and Review Commission estimated that unconstrained electricity demand could double within roughly a decade, driven primarily by data center growth. Meeting even a portion of that projected demand would require substantial additions to generation and transmission capacity.

Meanwhile, the rules governing how large new loads connect to the regional power grid remain unsettled.

On October 9, the Federal Energy Regulatory Commission rejected major portions of PJM Interconnection’s proposed Interim Resource Adequacy Service framework. PJM had sought to establish special arrangements for large new electricity customers, including provisions allowing some loads without matching new generation capacity to connect subject to curtailment during system emergencies.

FERC raised concerns about federal jurisdiction over retail service and potentially discriminatory treatment of large electricity customers. The commission approved PJM’s proposed large-load registry and definition but rejected the broader interim-service and bring-your-own-new-capacity provisions, leaving open the possibility of revised proposals.

The decision introduces another layer of uncertainty for Virginia developers seeking dependable paths to energization. Even when customers can demonstrate adequate financing and willingness to pay for infrastructure, the regional mechanisms governing when and under what conditions large new loads can receive service are still evolving.

Together, the changes point toward a more demanding financial equation: Securing access to megawatts is becoming inseparable from demonstrating the ability to pay for them, support the infrastructure that delivers them and manage the consequences if projected demand never fully materializes.

A Widening Divide Across the Development Pipeline

The cumulative effect of Virginia’s changing policies could produce a sharper divide among three categories of data center projects: existing operations, developments with established approvals or vested rights, and early-stage speculative proposals.

For the existing operating base, the immediate consequences are relatively limited. Virginia is not seeking to dismantle facilities already serving customers, although emerging standards for water use, noise, backup generation, emissions and grid flexibility could increase operating costs or require additional investment in existing infrastructure.

The second category comprises projects that have already secured zoning approvals, permits, utility commitments or legally established development rights. These facilities may enjoy significant advantages over competitors entering the approval process today, particularly where developers have made substantial investments in reliance on earlier government decisions.

But the distinction between an approved project and one with legally vested rights is becoming increasingly important. Under Virginia law, vested rights generally require a qualifying governmental action, good-faith reliance and substantial investment or obligations undertaken in pursuit of a specific development. Owning land or possessing favorable zoning does not, by itself, guarantee protection against subsequent regulatory changes.

That distinction could become particularly consequential if the administration’s proposal to require new local approvals for data centers exceeding 25 MW, regardless of prior authorizations, advances through the General Assembly.

The third category, early-stage speculative development, faces perhaps the greatest potential disruption.

Virginia’s framework explicitly calls for stronger upfront financial commitments to prevent proposed campuses from reserving land, transmission capacity and other infrastructure without ultimately being built. That objective strikes at a development model in which land acquisition, zoning, utility agreements, customer commitments and financing can advance on different timelines.

Large AI campuses are often announced with multibillion-dollar investment projections even though the power, tenants or financing needed for their ultimate buildout have not yet been secured. Under a more demanding approval and cost-allocation environment, developers could face greater pressure to substantiate those commitments earlier, before acquiring additional development rights or reserving scarce infrastructure capacity.

The implications extend to Virginia’s market for prospective data center land. Properties with confirmed utility access and defensible development rights could command increasing premiums, while sites dependent on uncertain power delivery, rezoning or speculative future demand may become less attractive to investors.

None of this necessarily means every element of a project must be finalized before approval. But it does suggest a shift in where risk resides, with more of the financial and regulatory uncertainty falling on developers before a facility reaches construction.

The emerging competitive advantage may belong not simply to those who control the most land, but to those who can demonstrate the clearest, most defensible path from acquisition to an operating data center.

Local Governments Tighten the Rules

Virginia’s two most important Northern Virginia data center jurisdictions were already restructuring their development processes before Spanberger introduced her statewide framework.

On September 22, the Prince William County Board of Supervisors approved a major reduction in its Data Center Opportunity Zone Overlay District, restructuring an area that had covered roughly 9,700 acres into a much narrower district expected to encompass approximately 3,641 acres.

The change substantially limits where data centers can proceed by right, without obtaining a special-use permit. Properties remaining within the revised overlay must meet one of five eligibility criteria, including provisions protecting certain previously advanced developments. A final eligibility window remains open through December 21, after which the county will publish an updated boundary map.

For new projects outside the overlay, the special-use permit process becomes the principal development pathway in eligible commercial and industrial zoning districts, giving county supervisors greater discretion over whether proposed facilities can proceed and under what conditions.

Loudoun County, meanwhile, had already eliminated most by-right data center development in March 2025, requiring new projects to obtain special-exception approval. In September 2026, its supervisors went further, voting to advance a proposal that could defer final board action on data center and electrical substation applications requiring legislative approval for up to 12 months.

The proposed Loudoun policy, scheduled for consideration October 20, would allow applications to continue through preliminary review and Planning Commission proceedings while delaying final board votes. If adopted, supervisors intend the pause to apply retroactively to September 15, subject to statutory deadlines and possible exceptions for grid-reliability projects.

County officials have emphasized that Virginia law does not permit a blanket moratorium on data center development. The proposed delay is instead intended to give Loudoun time to complete an ongoing review of data center locations, design requirements and operating standards, with that work expected to conclude in summer 2027.

A separate zoning dispute illustrates how the county’s increasingly restrictive approach is affecting even established hyperscale developers.

In July, Amazon submitted plans for more than 800,000 square feet of data centers on the 122-acre former George Washington University campus in Ashburn. Although the property lies within the Route 28 Tax District, where certain properties remain governed by older zoning provisions, Loudoun officials determined that the applicable 1972 ordinance does not permit data centers as a principal use.

The county’s zoning administrator issued that interpretation in July, and officials reaffirmed it publicly during the October 6 Board of Supervisors meeting. As a result, Amazon would need board approval to proceed with its proposed redevelopment. Portions of the property also carry additional land-use restrictions associated with its former educational purpose.

The dispute underscores the increasing importance of how historical zoning permissions are interpreted. Even within the industry’s most established market, ownership of a large, strategically located property does not necessarily establish an automatic right to develop a new data center campus.

For developers, the cumulative effect is a more complicated entitlement environment. State policymakers are seeking greater accountability for infrastructure and environmental costs, while local governments are asserting more discretion over the location, scale and conditions of future construction.

The result is not simply slower permitting. It is a shift in the balance of negotiating power, with developers increasingly required to demonstrate how individual projects fit within local land-use priorities before they can secure the approvals needed to move forward.

Growth Continues, but Under Different Terms

Henrico County offers an early example of how tighter local requirements can change the development pipeline. In June 2025, the county eliminated by-right data center development in industrial, business and office districts, requiring developers to seek provisional-use permits instead.

According to September 29 reporting by Virginia Business, Henrico has 37 data centers and approximately 17 previously approved facilities in its pipeline. Yet only one developer, Centra Logistics, had applied for a provisional-use permit under the new rules.

That limited application activity does not, by itself, establish that development demand has collapsed. The existing approved pipeline remains substantial, and developers may be adjusting to the revised process. But it illustrates how a jurisdiction can materially change the terms of future growth without disturbing projects already authorized.

The economic incentives to accommodate additional development remain considerable. Virginia’s Joint Legislative Audit and Review Commission estimated in 2024 that the industry supports approximately 74,000 jobs, $5.5 billion in labor income and $9.1 billion in annual state GDP. Most of that economic impact derives from construction rather than permanent data center operations, underscoring both the importance of continued investment and the distinction between short-term development activity and long-term employment.

Outside Northern Virginia, prospective projects are also beginning to reflect the state’s emphasis on geographic diversification, infrastructure accountability and community disclosure.

On September 22, the Western Virginia Regional Industrial Facility Authority publicly identified Clearview Dynamics as the company evaluating approximately 94 acres at Wood Haven Technology Park in Roanoke County for a potential data center development.

The project remains in due diligence, expected to continue through March 2027, with its ultimate power requirements still being evaluated. According to Roanoke County, Clearview has committed to paying for the water and electrical infrastructure required by the development, rather than placing those costs on the surrounding community. The proposed water source is Spring Hollow Reservoir.

Local officials explicitly connected their September disclosure to the transparency expectations established by Spanberger’s executive order. But the limits of that transparency became apparent on October 6, when the regional authority announced it had been released from its nondisclosure agreement with Clearview while continuing to withhold the identity of the company’s corporate parent, citing its obligation to protect confidential economic development information.

The distinction illustrates an unresolved tension in Virginia’s emerging approach: Greater public disclosure may become a central expectation for development, but determining how much information must be released, and when, remains a point of contention.

Meanwhile, projects are still receiving approval in jurisdictions where developers are prepared to negotiate detailed conditions.

On October 7, Stafford County supervisors voted 4–3 to approve the rezoning and associated electrical-substation permit for Falmouth Tech LLC’s Accokeek Center, a proposed two-building campus totaling approximately 590,000 square feet on 121 acres.

The approval followed debate over exceptions to the county’s residential setback requirements and included approximately $6.4 million in developer contributions for community priorities, along with restrictions on water use. Further site-plan and utility approvals remain necessary.

Taken together, the Henrico, Roanoke and Stafford examples suggest that Virginia’s development market is not simply moving toward a binary choice between approval and prohibition. Instead, local governments are exercising greater discretion over the conditions under which projects advance, while developers face growing pressure to demonstrate financial capacity, infrastructure responsibility and tangible community benefits.

Vested Rights Become a Strategic Asset

As Virginia tightens its development requirements, projects with established legal rights are taking on a new competitive significance.

A September 29 agreement between Amazon Web Services and King George County illustrates the stakes. The county formally recognized AWS’s vested rights to redevelop the former Birchwood Power Facility, a retired coal-fired power plant, and nearby industrial-zoned properties as part of a planned $6 billion data center investment.

The agreement also reflects the continuing importance of negotiating community benefits. AWS committed $10 million toward a county career and technical education school and agreed not to construct data center buildings on land adjacent to the Rappahannock River. The development is expected to create more than 100 jobs.

The arrangement demonstrates how established development rights can provide a foundation for large-scale investment while leaving room for negotiated environmental protections and community commitments.

In Loudoun County, the potential cost of challenging previously established development protections became apparent during the October 6 Board of Supervisors meeting.

County officials warned that rescinding a 2025 grandfathering resolution, which allows certain data center applications to proceed under earlier zoning rules, could expose Loudoun to as much as $60 million in litigation costs and potential liabilities. At least 15 pending applications remained covered by the resolution, representing approximately 10.5 million square feet of proposed development.

Rather than move forward with rescinding those protections, supervisors considered an independent audit to determine whether individual projects continued to qualify. That proposal, with an estimated cost of up to $200,000, was indefinitely tabled on a 7–2 vote. The grandfathering resolution remained in place.

The distinction between grandfathered applications and legally vested development rights is important. Loudoun’s resolution establishes eligibility for certain projects to continue under previous permitting rules, while Virginia’s statutory vested-rights protections require specific governmental actions, good-faith reliance and substantial development commitments. Neither status should be assumed merely because a developer owns land or has proposed a project.

Together, the Loudoun and King George cases underscore a changing development calculation. Established rights can shield projects from some consequences of shifting local policy, but their scope and enforceability may themselves become subjects of negotiation or litigation. For investors and developers, the legal certainty surrounding a site is becoming nearly as consequential as its access to power.

Virginia’s Next Competitive Test

The Commonwealth’s broader strategy nevertheless assumes continued growth. Spanberger’s October 1 Virginia Energy Plan explicitly seeks to accommodate rising electricity demand while ensuring that data centers bear the incremental infrastructure costs they create, demonstrate greater demand flexibility and support Virginia’s clean-energy and community objectives.

The policy direction represents a meaningful departure from the conditions that helped establish Northern Virginia’s leadership over the past two decades. Its original advantages included extraordinary fiber connectivity, proximity to Ashburn’s network ecosystem, historically competitive power costs, favorable tax treatment, specialized development expertise and a comparatively predictable permitting environment.

Those advantages have not disappeared. Virginia still possesses the country’s most established concentration of data center infrastructure and an extensive network of utilities, contractors, operators and technology companies supporting continued expansion.

But the requirements for translating those advantages into new capacity are becoming more demanding.

Developers increasingly face an environment in which power availability, transmission investment, land entitlement, environmental performance and community acceptance must be addressed as interconnected elements of project execution. Financially capable operators with established customers and defensible development rights may be better positioned to navigate those requirements. More speculative projects could face higher carrying costs, longer development timelines and greater uncertainty over whether their sites will ultimately be viable.

The consequences will not necessarily be uniform. Stronger financial commitments and infrastructure cost allocation could reduce speculative demand and protect existing ratepayers. At the same time, more discretionary approvals and regulatory uncertainty could delay projects that might otherwise proceed, potentially shifting investment toward competing markets.

Virginia’s challenge is therefore not simply to regulate data center growth more aggressively. It is to establish rules that make future development more accountable without undermining the predictability and investment certainty that helped build the industry’s largest U.S. market.

The next phase of Virginia’s data center economy will test whether the Commonwealth can maintain that balance—and whether developers can still deliver new capacity at the scale and speed the AI infrastructure market demands.
Shape
Shape
Stay Ahead

Explore More Insights

Stay ahead with more perspectives on cutting-edge power, infrastructure, energy,  bitcoin and AI solutions. Explore these articles to uncover strategies and insights shaping the future of industries.

Shape

SolarWinds launches Avior AI agents to automate network operations

The first Avior offering is a network engineering agent that can automate alert management, configuration automation, compliance checks, and incident remediation. “We started there because [the network is] kind of our bread and butter,” Childress explains. “Many of our customers, a large portion of our customers, are on our network

Read More »

Equinor plans tieback of Grimsnes discovery to Oseberg platform in North Sea

Equinor Energy AS made an oil and gas discovery in the Grimsnes prospect near Oseberg field in the North Sea about 15 km southwest of the Oseberg Sør (South) platform and 145 km west of Bergen in 96 m of water. Well 30/8-7 S, the fifth exploration well in production license (PL) 190, was drilled by the Deepsea Bergen semi-submersible drilling rig to a vertical depth of 3,752 m subsea. It was terminated in the Drake formation in the Lower Jurassic, the Norwegian Offshore Directorate reported. The primary exploration target was to prove petroleum in Middle Jurassic reservoir rocks in the Tarbert formation. The secondary target was to prove petroleum in Middle Jurassic rocks in the Ness and Etive formations. The well encountered a combined oil and gas column totaling 54 m (39-m gas column, 15-m oil column) in the Tarbert formation. The total thickness of the Tarbert formation was 264 m, 111 m of which were sandstone with moderate to good reservoir properties. In the secondary exploration target in the Ness formation, the well encountered a sandstone layer totaling 289 m with variable reservoir quality from poor to very good. The reservoir was aquiferous with a few potential hydrocarbon-filled zones. In the Etive formation, the well encountered aquiferous sandstones totaling 10 m, with moderate reservoir quality. The preliminary volume estimate of the discovery is 19-50 MMboe (3-8 million std cu m). Data has been collected and samples have been taken. The well has been permanently plugged, and the Deepsea Bergen rig will now proceed to Visund Sør field to drill a development well. Equinor plans to quickly tie the discovery back to existing subsea infrastructure and produce the volumes through the Oseberg Sør platform. Grimsnes will most likely be developed with 2-3 wells in a standard 4-slot template. The discovery

Read More »

DOE Alternative Fuels and Feedstocks Office Announces Intent to Award Up to $60 Million for Innovative Chemical, Fuel, and Fertilizer Technologies

WASHINGTON—The U.S. Department of Energy’s (DOE) Alternative Fuels and Feedstocks Office (AFFO) today announced its intent to award up to $60 million to expand domestic energy production and distribution through novel, high-impact chemicals, fertilizers, fuels, and feedstock technologies. The funding opportunity is in accordance with President Trump’s Executive Order, Unleashing American Energy, which calls for expanding domestic supply chains and the production of American energy to lower prices for hardworking Americans, including farmers, ranchers, and small businesses. “President Trump’s administration is strengthening America’s agricultural and energy sectors – both critical backbones of our prosperity and security – enabling our energy independence and benefiting all hardworking American families,” said Assistant Secretary Audrey Robertson. “Under President Trump’s and Energy Secretary Chris Wright’s leadership, we are empowering farmers, ranchers, and energy producers to lower prices, unleash American-made energy dominance, build a strong multi-generational workforce, and ensure the long-term prosperity and success for our great country.” DOE will seek research, development and scale-up projects that harness existing biomass, hydrogen, and pipeline resources to expand domestic energy production, distribution, and fertilizer technologies. AFFO expects to issue a notice of funding opportunity (NOFO) in November 2026, addressing the following topic areas: Topic Area 1: Biointermediate Depots – Enhance the production of liquid intermediate-products that are made from biomass and establish pilot sites to produce traditional intermediate products such as high impact chemicals, sugars, bio-crudes, or bio-oils, from biomass and wastes.  Topic Area 2: Refinery Integration – Advance the production of commodity chemicals and fuels from alternative feedstocks using existing refinery assets and achieving production-costs that enable competitive market pricing.  Topic Area 3: Pilot Site for Hydrogen/Natural Gas Blending – Establish pilot sites for hydrogen and natural gas blending and the distribution/utilization of those blends to improve the reliability, scalability, suitability, performance and durability of distribution networks.

Read More »

Energy Department Releases Emissions Value Request Process for 45Z Fuel Production Credit

WASHINGTON—The U.S. Department of Energy (DOE) Alternative Fuels and Feedstocks Office (AFFO) released a pre-publication draft of a federal register notice announcing the Emissions Value Request (EVR) process for the 45Z fuel production tax credit. Modified and extended under the Working Families Tax Cut, the Clean Fuel Production Tax Credit (Internal Revenue Code Section 45Z) provides a production incentive for certain feedstocks produced in the United States, Mexico, or Canada. “Thanks to President Trump’s Working Families Tax Cut, we are creating new opportunities for American farmers and fuel producers to strengthen domestic energy production, reduce costs, and unleash American energy dominance,” said Assistant Secretary of Energy Audrey Robertson. “Through the Department of Energy’s new 45Z Emissions Value Request process, we are expanding opportunities for American fuel producers to access critical tax incentives, supporting rural economies, and bringing more American-made fuels to market. In short: putting American energy first.” Transportation fuel producers seeking to claim the tax credit must obtain the life cycle greenhouse gas emissions rate of their transportation fuel using the applicable rate table for Section 45Z. If the fuel’s type, primary feedstock, or pathway is not included in the rate table, fuel producers must petition the Secretary of Treasury for a provisional emission rate (PER). The 45Z EVR process is the route through which fuel producers can obtain a rate value from DOE and petition U.S. Treasury for a PER. To request an emissions value from DOE, stakeholders must follow the EVR Application Instructions to submit the following requested materials: Engineering information/analyses consistent with the specified section of the front-end engineering and design (FEED) study or similar indication of project maturity, as determined by DOE. A completed EVR form. In addition to the required documents, an applicant also has the option to include additional information that may be

Read More »

IEA: Oil supply rebound remains fragile; diesel tightness persists

Supply recovery at risk Global oil supply increased by 2.5 million b/d month over month to 102.3 million b/d in September. OPEC+ accounted for 2.1 million b/d of the increase, led by Saudi Arabia. Renewed attacks on tankers and energy infrastructure threaten further gains, IEA warned. Despite September’s rebound, global supply is forecast to decline by 5.8 million b/d to 100.7 million b/d this year, before rising by 7.7 million b/d in 2027. Next year’s recovery remains contingent on sustained improvements in Hormuz flows. “Crude oil exports from Gulf producers, led by Saudi Arabia, surged by 4.4 million b/d to 13.9 million b/d in September, reaching over 75% of pre-war levels as supply recovered strongly and inventories were drawn down. Robust Gulf of Oman ship-to-ship transfers helped lift total oil flows through the Strait of Hormuz by 3.7 million b/d to 10.9 million b/d, while the swift return of East-West pipeline flows increased overall bypass exports by 970,000 b/d to 5.6 million b/d. The strong rebound raised estimated global supply for third-quarter 2026 by 190,000 b/d compared with last month’s Report. However, due to heightened security concerns amid increased Houthi attacks in the region in October, we have left the projections for the remainder of the year largely unchanged,” IEA said. North Sea Dated averaged $116.89/bbl in September, up $26.17/bbl from August. Diesel, inventories under pressure Global diesel exports in September were nearly 700,000 b/d below year-earlier levels, as increased shipments from other suppliers only partly offset losses from Russia and the Middle East. IEA expects diesel market tightness to extend well into 2027. “Refined product and LPG shipments from the Middle East have risen much more slowly than crude oil flows and remain below half of their pre-war levels. Refined products rose by 210,000 b/d to 1.9 million b/d

Read More »

Energy Department Awards $49.8 Million to Advance Methane Hydrate Production Research on Alaska North Slope

WASHINGTON — The U.S. Department of Energy’s (DOE) Hydrocarbons and Geothermal Energy Office (HGEO) today announced a five-year contract valued at up to $49.8 million awarded to ASRC Consulting and Environmental Services, LLC (ACES), a subsidiary of Arctic Slope Regional Corporation Energy Services Alaska, Inc. (AES). The contract will advance research and production testing of methane hydrates, a potential source of natural gas found in subsurface formations on Alaska’s North Slope.  The award supports President Trump’s goal of unleashing American energy and U.S. Energy Secretary Chris Wright’s focus on advancing energy addition and American innovation by building the scientific and engineering knowledge needed to evaluate methane hydrates as a potential future domestic energy resource. The work will build on technical insights from prior production testing while maintaining a unique research site in the Prudhoe Bay Unit for potential follow-on operations.  “President Trump has made clear that America should use its extraordinary energy resources and innovation to strengthen our energy security and global leadership,” said DOE Acting Assistant Secretary of the Hydrocarbons and Geothermal Energy Office Curt Coccodrilli. “This investment will help build on years of field research in Alaska to move methane hydrate research from scientific discovery toward the real-world testing needed to determine its commercial production potential.”  Gas hydrates are naturally occurring, ice-like crystalline solids that hold vast quantities of natural gas beneath the permafrost and offshore. Unlocking these resources represents a vital component of the United States’ long-term energy strategy to secure abundant domestic supplies. Alaska’s North Slope research site provides a unique setting for long-duration field research because hydrate-bearing reservoirs can be studied using established infrastructure and continuously monitored wells.  The project will proceed in two phases. Phase 1 will maintain the existing research site and supporting equipment and develop detailed plans for a potential follow-on production test. Should

Read More »

HPCL taps Technip Energies for EPC on new Mumbai refinery unit

Hindustan Petroleum Corp. Ltd. (HPCL) has awarded Technip Energies an engineering, procurement, and construction (EPC) contract for two major units in the lube modernization and bottoms upgradation (LMBU) project at its 9.5-million tonne/year (tpy) Mumbai refinery in Maharashtra, India. The work covers a 550,000-tpy integrated hydrocracker and catalytic dewaxing (IHCD) unit and an 850,000-tpy solvent deasphalting (SDA) unit. Both will be integrated into the operating refinery, Technip Energies said in a release Oct. 12. The new units aim to increase production of lube oil base stocks (LOBS) used in automotive engine oils and industrial lubricants, while upgrading heavier refinery streams into higher-value products, according to the service provider. While Technip Energies did not reveal the precise value of the contract, the company confirmed the order would amount to between €250-500 million of revenue. This latest EPC contract for the project’s IHCD and SDA units follows HPCL’s earlier award to Chevron Lummus Global for licensing of technologies to outfit the IHCD unit. Project overview HPCL’s LMBU project is designed to raise the Mumbai refinery’s output of LOBS to 764,000 tpy from 475,000 tpy, including production of Group II+ and Group III base stocks. The project is also expected to increase bitumen production by about 487,000 tpy through fuel oil upgrading, as well as improve the refinery’s yield of distillate by about 4%, HPCL said in a release Jan. 23, 2025. HPCL began work on the LMBU project during the third quarter of its 2025 fiscal year at an estimated project cost of 46.79 billion rupees (US$541.1 million). Scheduled to be fully completed in March 2028, the LMBU project had reached 9.9% physical completion as of Mar. 31, 2026, at a then-current project cost of 57.40 billion rupees (US$600.4 million), HPCL said in an investor presentation dated May 13, 2026.

Read More »

Virginia’s New Data Center Bargain: Power, Permits and the Right to Build

What Took Effect—and What Still Requires Legislation Spanberger laid out the administration’s rationale in announcing the framework: “In the years before I took office, data centers came to Virginia and the Commonwealth did not have a clear or coordinated plan to address their impacts on Virginians — on their electric bills, their water, their land, their air, or their quality of life. That changes today. I have said many times that Virginia should be leading the nation in setting the highest standards for this industry. And now, I believe we are doing just that.” The distinction between what Virginia has already implemented and what the administration intends to pursue is consequential. Executive Order 22 establishes immediate directives for state agencies, while significant portions of the broader Data Center Accountability Framework remain proposals for the 2027 General Assembly or future regulatory action. Among the immediate changes, executive-branch agencies are prohibited from entering into or enforcing new nondisclosure agreements that conceal material information about proposed commercial data centers, public incentives, resource demands or community impacts. Existing contractual commitments are preserved, with limited exceptions contemplated for extraordinary circumstances, including national security. The prohibition does not yet extend automatically to local governments. The order also excludes new data center projects with anticipated peak electrical demand of 25 MW or greater from the Virginia Business Ready Sites Program and similar discretionary state site-readiness and expedited-review assistance. A separate, potentially more consequential proposal would eliminate by-right development approval for data centers using more than 25 MW, requiring local approval even for projects with prior authorizations. That provision has not been enacted statewide and could introduce significant legal questions concerning established development rights. The administration is also accelerating environmental oversight. Within 120 days of the order, the Office of the Chief Energy Officer must publish an initial

Read More »

OCP 2026: Agentic AI Drives the Data Center’s Chip-to-Grid Transformation

NVIDIA Opens More of the AI Factory Architecture NVIDIA’s Ian Buck closed the opening keynote program with an extensive presentation covering Vera Rubin systems, open rack designs, networking, power delivery and AI factory software. The company announced additional contributions to OCP based on its third-generation MGX 1.2 reference architecture. The specification includes high-density liquid-cooled computing systems, improved cooling connections, standardized power interfaces and modular mechanical designs. Buck emphasized that these developments are as much about manufacturing and serviceability as they are about computational performance. He described how NVIDIA reduced the assembly time for a compute tray from approximately 90 minutes in the Grace Blackwell generation to roughly one minute for Vera Rubin through simplified mechanical construction and more automated assembly. At the scale of thousands of racks, those manufacturing improvements can materially influence deployment schedules. NVIDIA also previewed its next-generation Vera Rubin Ultra architecture, designed to interconnect 576 GPUs using an advanced NVLink fabric with co-packaged optics. Open Data Center and Grid Resilience Specifications For data center developers and operators, however, NVIDIA’s most consequential OCP contributions may lie outside the computing rack. NVIDIA, AMD, Google and Meta have published an Open Data Center Specification, currently at version 0.7, intended to establish common design principles for AI factory facilities. The specification addresses power architecture, cooling infrastructure and physical layout, helping equipment suppliers and developers coordinate around shared infrastructure requirements. That shared facilities work unfolds alongside vendor-specific programs such as NVIDIA’s DSX Ready, which establishes qualification requirements for battery energy storage and liquid cooling equipment supporting its AI factory designs. NVIDIA also joined Google, Meta and Microsoft in publishing an OCP Grid Resilience Specification addressing the behavior of large AI installations during grid disturbances. The specification establishes expectations for facilities to remain connected, respond automatically to disturbances and recover toward normal operating

Read More »

NetBox Labs adds network design templates and AI agents to streamline infrastructure operations

“This is infrastructure, and so if an agent does the wrong thing, it breaks the company,” Beevers said. NetBox Designs turns repeatable infrastructure into templates AI data centers are full of racks that are almost all identical in design. Teams do not want to lay out each one by hand. The same applies to a retail chain with small, medium, and large store formats, where the IT footprint needs to line up. NetBox Designs, now in public preview, targets that repetition. Designs work like “templatized Lego bricks for infrastructure,” Beevers said. A team defines a site, rack or IP plan once and sets its parameters. NetBox then renders the plan as many times as needed, down to the low-level components and their configuration. That includes assigning IP addresses, prefixes, and virtual LANs across a fabric. The goal is to speed design down to the component level, reduce manual error and compress time to market.

Read More »

AMD unveils Helion as agentic AI fuels demand for data center CPUs

AMD has introduced Helion, an open blueprint for data center racks that aims to give CPUs a larger role in running AI agents while allowing customers to configure GPU resources around their inference requirements. Based on Open Compute Project (OCP) specifications, the architecture supports different combinations of computing hardware. AMD cited examples including CPU-only racks for hyperscalers, powered by sixth-generation EPYC processors with up to 32,768 cores, and all-in-one enterprise racks accommodating up to 16 Instinct MI350P GPUs. AMD has listed networking bandwidth of up to 102 Tbps for Helion, although the company has not specified how that figure is calculated. The specification represents a planned rack capability rather than demonstrated performance in customer environments.

Read More »

Land & Expand: North America’s Data Center Pipeline Expands Under Pressure

Land & Expand is Data Center Frontier’s periodic look at the latest data center development news, including new sites, land acquisitions and campus expansions across North America. This latest installment finds the development pipeline continuing to expand, even as the requirements for bringing large-scale projects online grow more complicated. Developers are securing land, planning new power infrastructure and advancing campuses measured in hundreds of megawatts or more. At the same time, local governments and residents are demanding greater clarity on electricity costs, water consumption, noise, tax incentives and the long-term effects of industrial-scale computing facilities. A succession of development disclosures and project milestones through September and early October 2026 illustrates both the geographical reach of North America’s expanding data center pipeline and the growing difficulty of measuring how much proposed capacity will ultimately be delivered. The projects range from preliminary discussions and newly secured development sites to campuses already under construction. Some are advancing through formal permitting and power studies; others remain contingent on customers, financing or local approvals. Together, they reveal an industry still expanding aggressively, but operating under increasingly complex development conditions. Fluidstack: Cameron County, Texas — Up to 1.5 GW One of the largest newly disclosed projects is Fluidstack’s AI data center development in Cameron County in the Rio Grande Valley. The project surfaced publicly September 10 when Cameron County announced that it had issued Fluidstack a worksite permit for property near Harlingen. The permit authorizes preliminary site work, including grading, utilities and related infrastructure, rather than construction of the data center buildings themselves. Fluidstack subsequently disclosed considerably more detail on September 21, saying construction had begun on a $4 billion first phase capable of supporting as much as 1.5 GW. Fluidstack expects the project to generate more than 2,500 construction jobs and several hundred permanent positions. 

Read More »

DCF Global: Five Markets Redrawing the AI Infrastructure Map

The Global Constraint Is Execution These five markets demonstrate that the worldwide AI infrastructure buildout is no longer organized around a single development model. Spain is using permitting reform to attract investment. China is concentrating construction around energy resources. India is translating enormous capital commitments into an expanding development pipeline. Latin America is combining hyperscale growth with national industrial objectives. And Southeast Asia is creating interconnected infrastructure markets whose boundaries increasingly extend beyond individual cities and countries. Not every market is competing for the same business. Sovereign cloud services, enterprise applications, AI training clusters, and large-scale inference platforms carry different requirements involving power, connectivity, latency, data residency, and operating economics. But the infrastructure questions remain remarkably consistent. Can a project obtain enough electricity? Can transmission and supporting networks be delivered on schedule? Will the supply chain provide the required equipment? Can the facility be constructed and commissioned efficiently? And will the development retain the regulatory certainty and community acceptance required to operate for decades? The gap between announced development and actual capacity is becoming a defining measurement of the industry. Cushman & Wakefield estimates that Asia-Pacific alone had approximately 26.5 GW of data center capacity in its development pipeline during H1 2026. Of that total, roughly 4.8 GW was under construction, with another 21.7 GW in planning. Those figures reveal both the extraordinary scale of the opportunity and the considerable infrastructure work still required to realize it. What the Global Buildout Means for North America For U.S. data center operators, developers, engineering firms, equipment suppliers, and investors, international expansion is not a separate story. It is increasingly part of the same global competition for capital, equipment, power infrastructure, and specialized expertise. The transformers, switchgear, generators, advanced cooling systems, fiber networks, and electrical distribution equipment required by a major AI campus

Read More »

Microsoft will invest $80B in AI data centers in fiscal 2025

And Microsoft isn’t the only one that is ramping up its investments into AI-enabled data centers. Rival cloud service providers are all investing in either upgrading or opening new data centers to capture a larger chunk of business from developers and users of large language models (LLMs).  In a report published in October 2024, Bloomberg Intelligence estimated that demand for generative AI would push Microsoft, AWS, Google, Oracle, Meta, and Apple would between them devote $200 billion to capex in 2025, up from $110 billion in 2023. Microsoft is one of the biggest spenders, followed closely by Google and AWS, Bloomberg Intelligence said. Its estimate of Microsoft’s capital spending on AI, at $62.4 billion for calendar 2025, is lower than Smith’s claim that the company will invest $80 billion in the fiscal year to June 30, 2025. Both figures, though, are way higher than Microsoft’s 2020 capital expenditure of “just” $17.6 billion. The majority of the increased spending is tied to cloud services and the expansion of AI infrastructure needed to provide compute capacity for OpenAI workloads. Separately, last October Amazon CEO Andy Jassy said his company planned total capex spend of $75 billion in 2024 and even more in 2025, with much of it going to AWS, its cloud computing division.

Read More »

John Deere unveils more autonomous farm machines to address skill labor shortage

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More Self-driving tractors might be the path to self-driving cars. John Deere has revealed a new line of autonomous machines and tech across agriculture, construction and commercial landscaping. The Moline, Illinois-based John Deere has been in business for 187 years, yet it’s been a regular as a non-tech company showing off technology at the big tech trade show in Las Vegas and is back at CES 2025 with more autonomous tractors and other vehicles. This is not something we usually cover, but John Deere has a lot of data that is interesting in the big picture of tech. The message from the company is that there aren’t enough skilled farm laborers to do the work that its customers need. It’s been a challenge for most of the last two decades, said Jahmy Hindman, CTO at John Deere, in a briefing. Much of the tech will come this fall and after that. He noted that the average farmer in the U.S. is over 58 and works 12 to 18 hours a day to grow food for us. And he said the American Farm Bureau Federation estimates there are roughly 2.4 million farm jobs that need to be filled annually; and the agricultural work force continues to shrink. (This is my hint to the anti-immigration crowd). John Deere’s autonomous 9RX Tractor. Farmers can oversee it using an app. While each of these industries experiences their own set of challenges, a commonality across all is skilled labor availability. In construction, about 80% percent of contractors struggle to find skilled labor. And in commercial landscaping, 86% of landscaping business owners can’t find labor to fill open positions, he said. “They have to figure out how to do

Read More »

2025 playbook for enterprise AI success, from agents to evals

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More 2025 is poised to be a pivotal year for enterprise AI. The past year has seen rapid innovation, and this year will see the same. This has made it more critical than ever to revisit your AI strategy to stay competitive and create value for your customers. From scaling AI agents to optimizing costs, here are the five critical areas enterprises should prioritize for their AI strategy this year. 1. Agents: the next generation of automation AI agents are no longer theoretical. In 2025, they’re indispensable tools for enterprises looking to streamline operations and enhance customer interactions. Unlike traditional software, agents powered by large language models (LLMs) can make nuanced decisions, navigate complex multi-step tasks, and integrate seamlessly with tools and APIs. At the start of 2024, agents were not ready for prime time, making frustrating mistakes like hallucinating URLs. They started getting better as frontier large language models themselves improved. “Let me put it this way,” said Sam Witteveen, cofounder of Red Dragon, a company that develops agents for companies, and that recently reviewed the 48 agents it built last year. “Interestingly, the ones that we built at the start of the year, a lot of those worked way better at the end of the year just because the models got better.” Witteveen shared this in the video podcast we filmed to discuss these five big trends in detail. Models are getting better and hallucinating less, and they’re also being trained to do agentic tasks. Another feature that the model providers are researching is a way to use the LLM as a judge, and as models get cheaper (something we’ll cover below), companies can use three or more models to

Read More »

OpenAI’s red teaming innovations define new essentials for security leaders in the AI era

Join our daily and weekly newsletters for the latest updates and exclusive content on industry-leading AI coverage. Learn More OpenAI has taken a more aggressive approach to red teaming than its AI competitors, demonstrating its security teams’ advanced capabilities in two areas: multi-step reinforcement and external red teaming. OpenAI recently released two papers that set a new competitive standard for improving the quality, reliability and safety of AI models in these two techniques and more. The first paper, “OpenAI’s Approach to External Red Teaming for AI Models and Systems,” reports that specialized teams outside the company have proven effective in uncovering vulnerabilities that might otherwise have made it into a released model because in-house testing techniques may have missed them. In the second paper, “Diverse and Effective Red Teaming with Auto-Generated Rewards and Multi-Step Reinforcement Learning,” OpenAI introduces an automated framework that relies on iterative reinforcement learning to generate a broad spectrum of novel, wide-ranging attacks. Going all-in on red teaming pays practical, competitive dividends It’s encouraging to see competitive intensity in red teaming growing among AI companies. When Anthropic released its AI red team guidelines in June of last year, it joined AI providers including Google, Microsoft, Nvidia, OpenAI, and even the U.S.’s National Institute of Standards and Technology (NIST), which all had released red teaming frameworks. Investing heavily in red teaming yields tangible benefits for security leaders in any organization. OpenAI’s paper on external red teaming provides a detailed analysis of how the company strives to create specialized external teams that include cybersecurity and subject matter experts. The goal is to see if knowledgeable external teams can defeat models’ security perimeters and find gaps in their security, biases and controls that prompt-based testing couldn’t find. What makes OpenAI’s recent papers noteworthy is how well they define using human-in-the-middle

Read More »