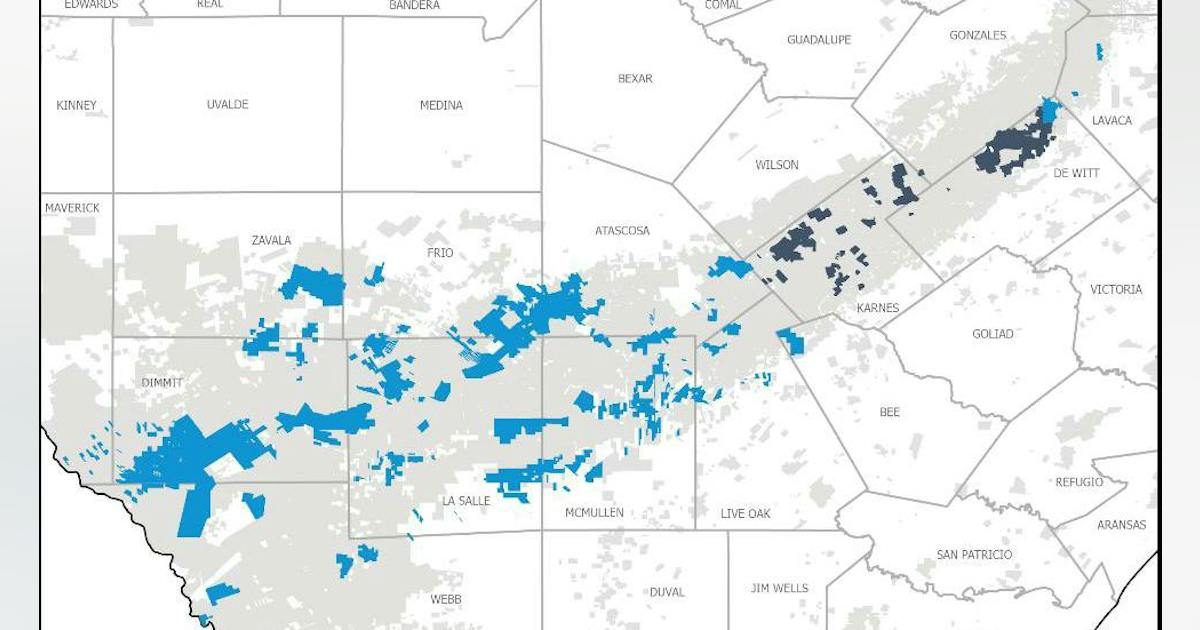
The acquisition continues a rapid buildout of Crescent’s Eagle Ford position, where the company has completed nine acquisitions since June 2023. Following closing, Crescent expects total production of about 400,000 boe/d, including roughly 170,000 b/d of oil.
Management said the value proposition centers on operational improvements rather than a material increase in activity levels.
Operations upside
Asked whether Crescent planned to maintain Devon’s current 2-3-rig development program, Rockecharlie said the company expects to keep activity at roughly the same pace.
By folding the assets into the company, he said, “we see significant capital allocation flexibility,” he said. “We think we’re going to deliver effectively the same production with less capital, just more capital efficiency, which is greater free cash flow for investors.”
Crescent expects to realize about $140 million in annual synergies, fully captured by the end of 2027, across drilling and completions, lease operating expenses, and marketing. Management said most of those gains are expected to come from drilling and completion efficiencies, including longer laterals and improved surface designs.
“Across our five most recent acquisitions, we’ve increased average lateral length by more than 25% versus previous operators, driving a step change in cost structure, increasing returns, and lowering breakevens,” Rynd said.
“Most of this is pretty simple and pretty straightforward… increasing lateral lengths and taking advantage of scale,” said chief operating officer Joey Hall.
Calling the acreage a familiar operating area, Hall added: “This is our backyard. We understand these assets. We’ve had line of sight into them for over 10 years.”
Hall expanded on the opportunity presented.
“Going from an average of 6,500 ft to 11,500 ft, that’s a step change in cost structure. We’ve been doing this across our acreage, so we’re confident we can execute on it and [we’re] looking forward to hitting that target.”
Rockecharlie also cited the assets’ ownership history as a source of potential upside.
“These assets were in a pretty wonky JV structure through multiple operators over the years that just got unwound last year. So there’s a lot to do here,” he said.
Devon sharpens focus
For Devon, the divestiture follows investor calls for additional asset sales after the company’s $22-billion acquisition of Coterra Energy Inc. and reflects a broader effort to concentrate capital on its highest return Permian basin opportunities.